Healthcare mid-year public market update
Hospitalogists,
They’ve made the grave mistake of giving me access to S&P Capital IQ.
So today’s update is a fun one. Hospitalogy OGs back in the day might remember I made a custom index called the Hospitalogy Index, comprised of healthcare services, distributors, and tech companies - very niche, very industry specific. Now, given I have access to the Cap IQ platform, I’ll periodically provide updates on this select batch of healthcare companies along with their relative performance and valuation.
I’ll include the full list below alongside the data. If there are any companies you think are missing, give me a shout. If there are any ways you gather intel through Cap IQ that would be useful to know, feel free to reply and let me know!
(Thanks to S&P Capital IQ for giving me access to the platform - appreciate it fam!)
P.S. - I am inevitable.
BLAKE’S BREAKDOWN
Introducing the Hospitalogy IndexCopy anchor linkCopied
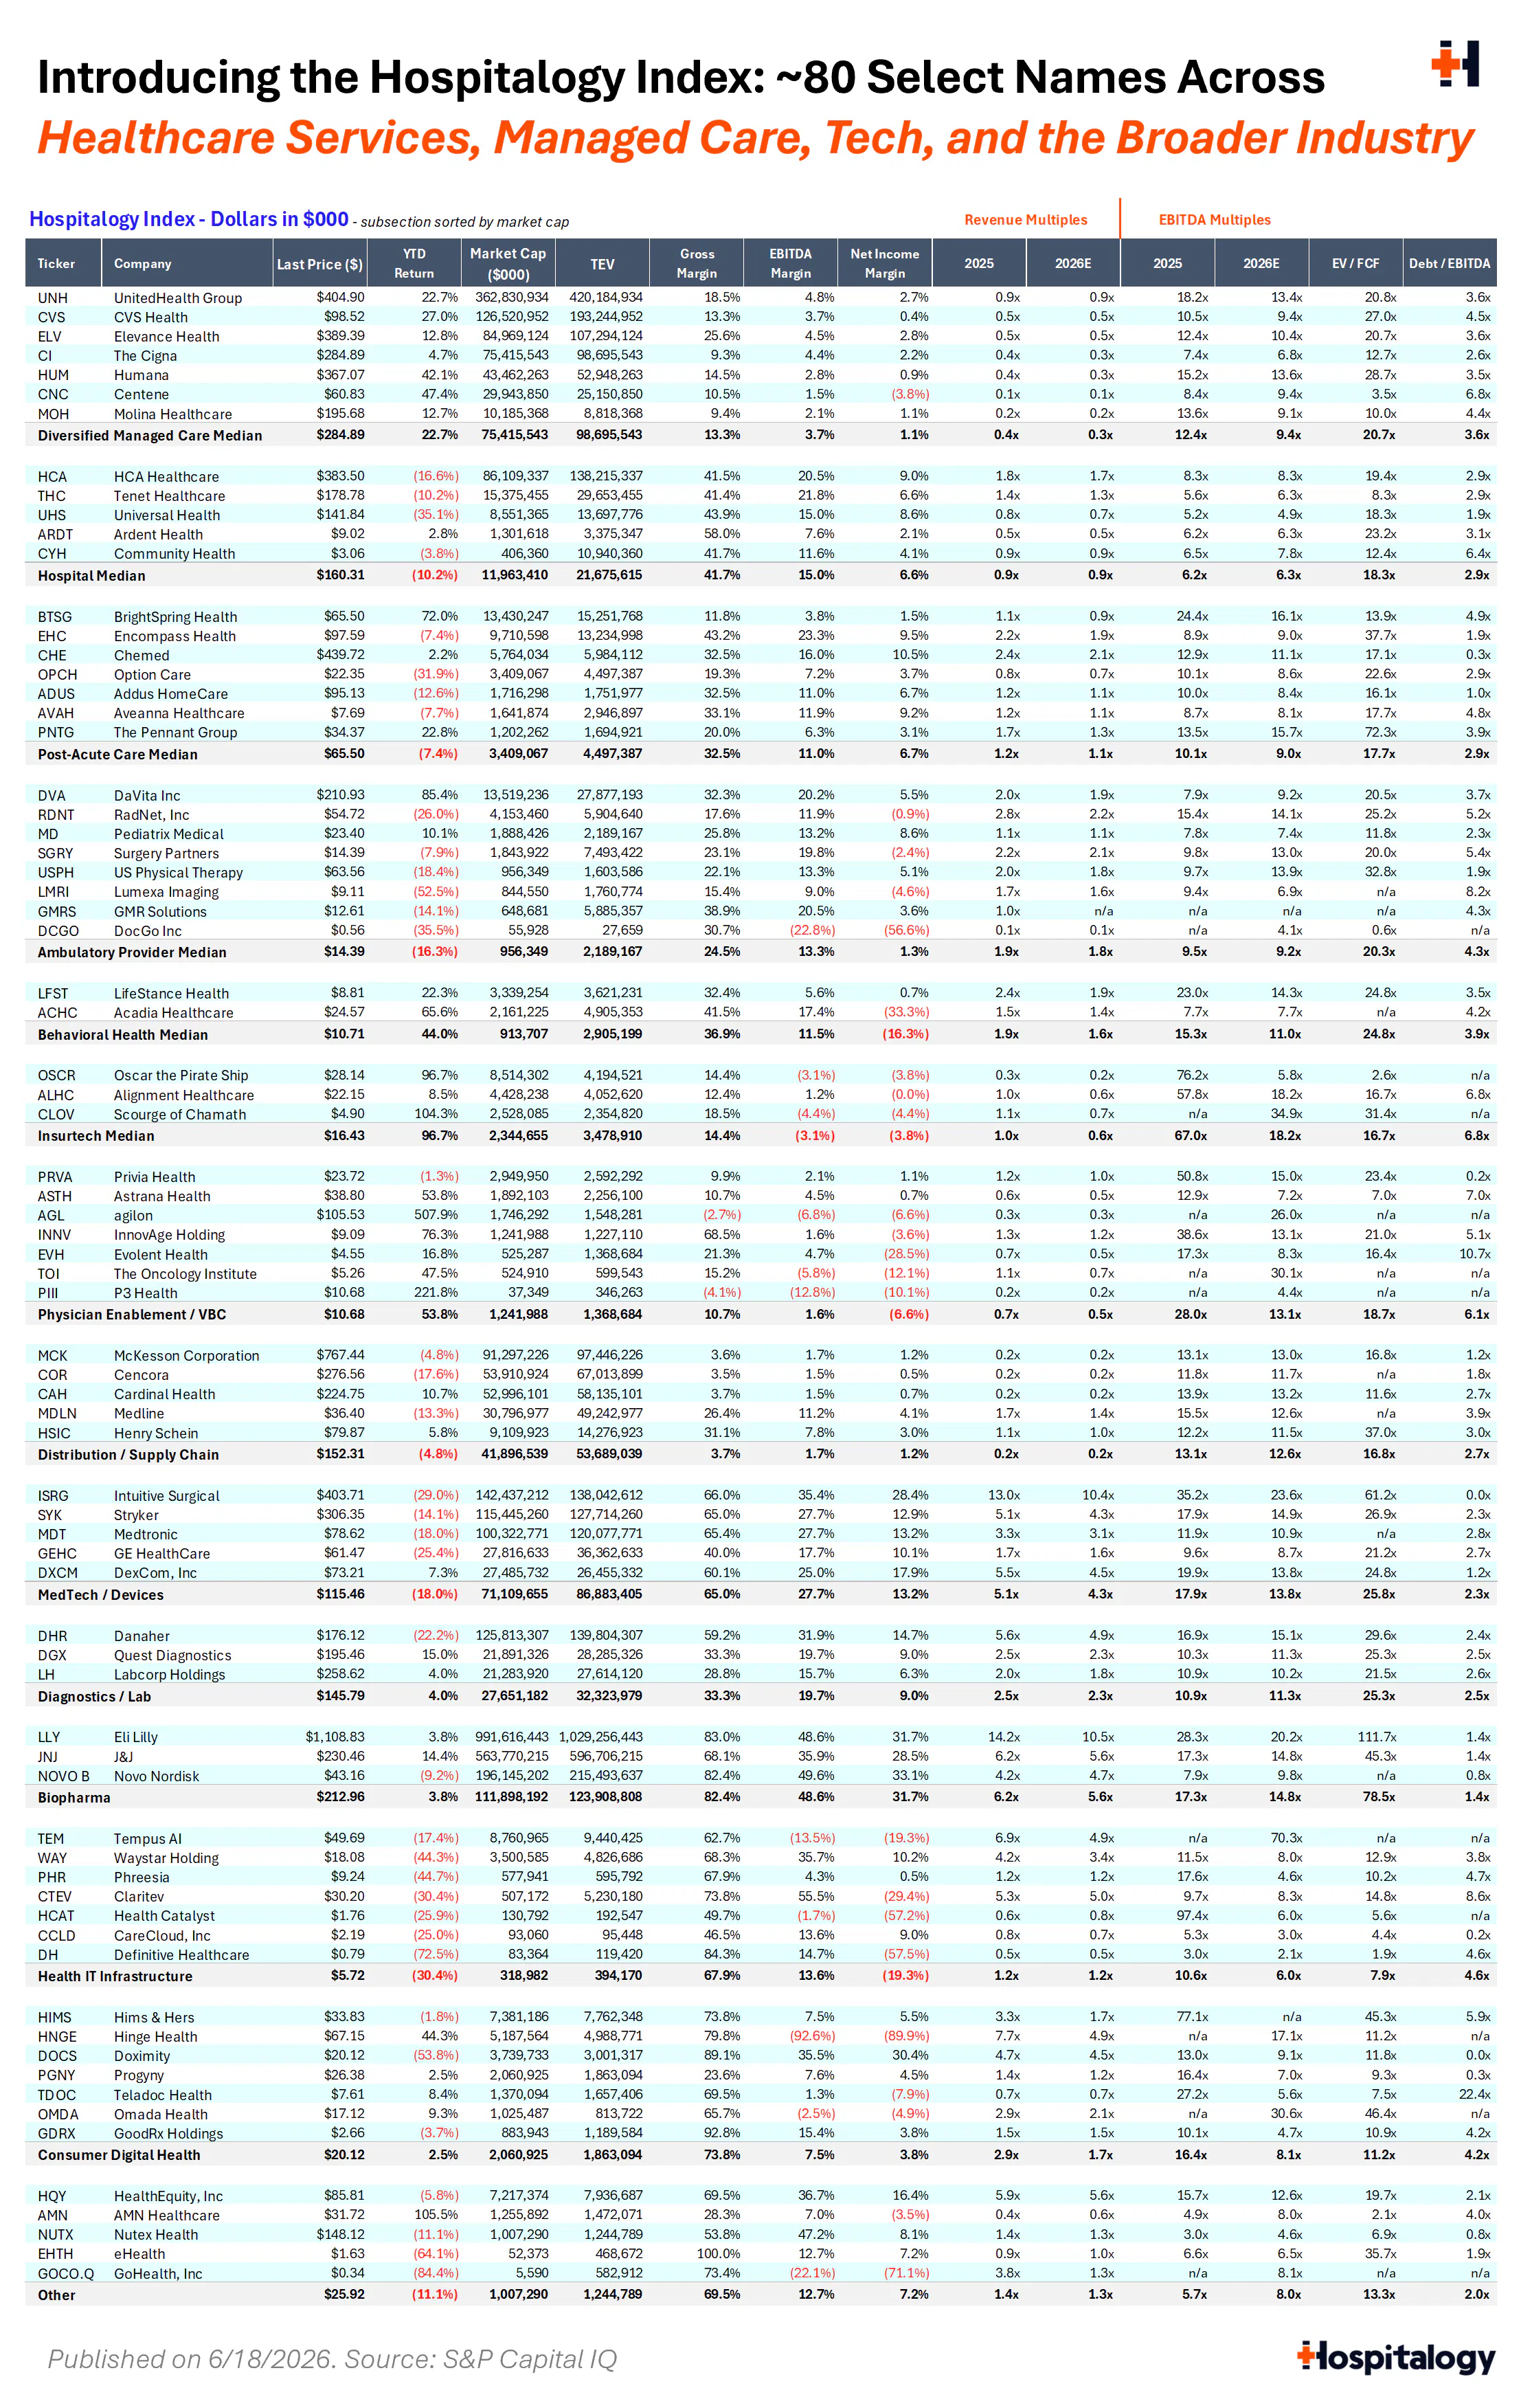
Here are the constituents of the Hospitalogy Index. There’s a slant toward healthcare services, managed care, and technology along with other key stakeholders in the ecosystem (I have about 7 more names to add after reviewing the list post-production):
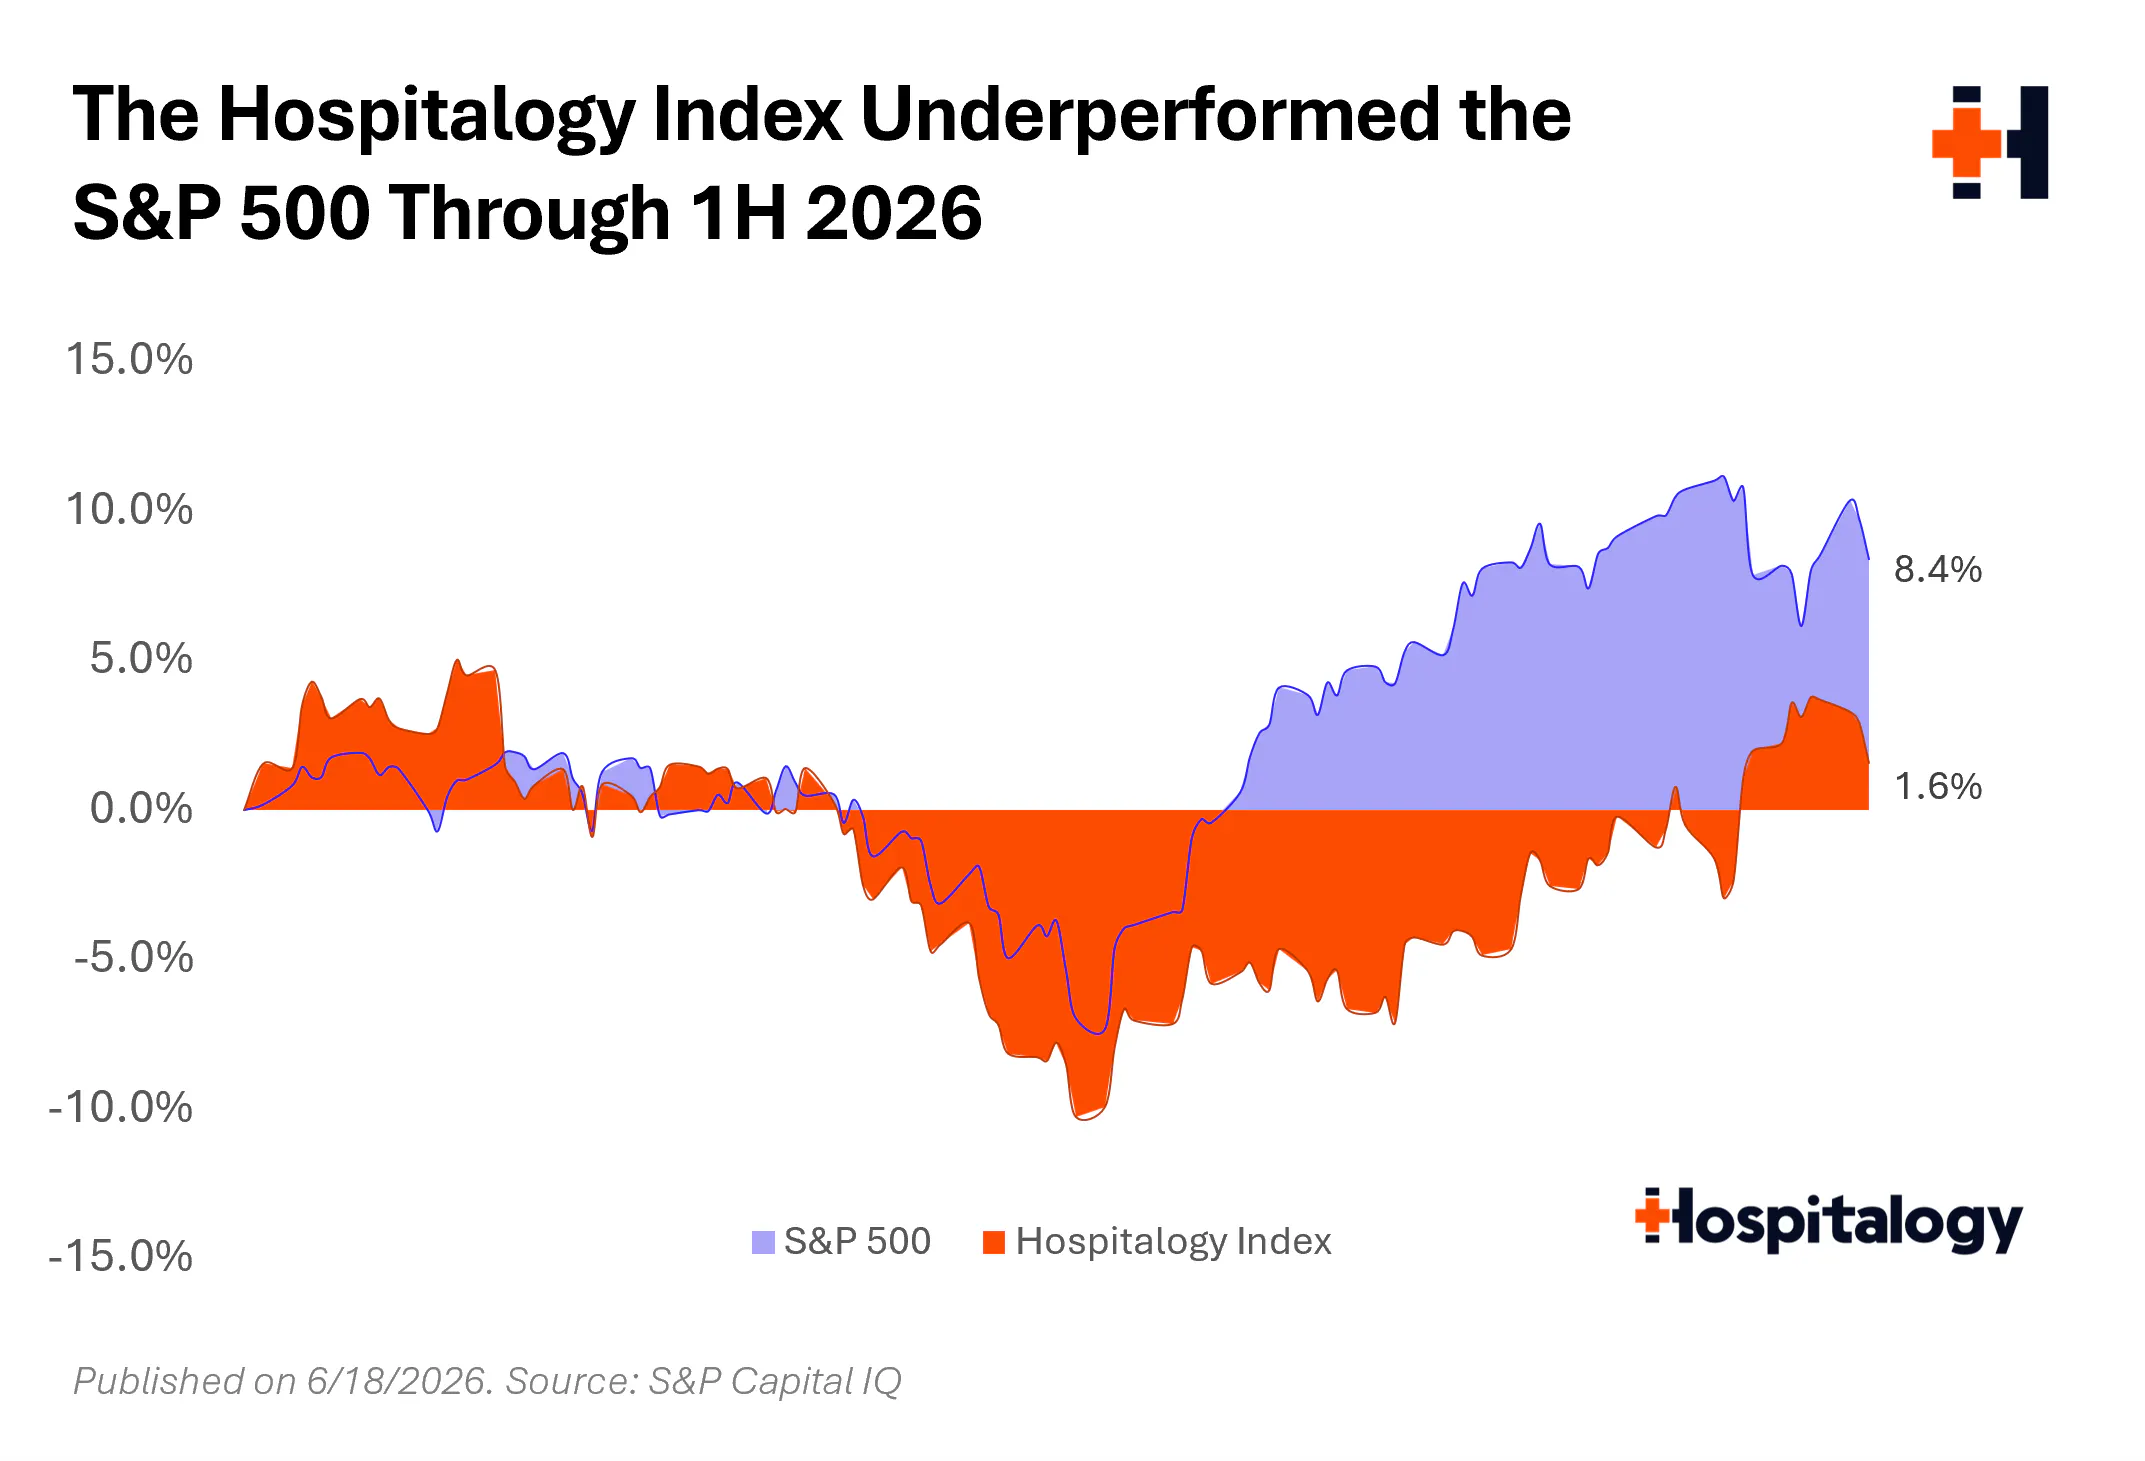
When putting these names into a market cap-weighted index against the S&P 500, these 75 or so names underperformed the broader market by a notable margin:
Top returners so far are names where investors are expecting a rebound, particularly in value-based care, with agilon and P3 Health Partners taking some of the top spots. Clover and Oscar are right there too - Oscar outperforming on expectations despite a shrinking ACA market, and Clover with winning its Stars lawsuit. Great stuff, Chamath. We’re on the up and up.
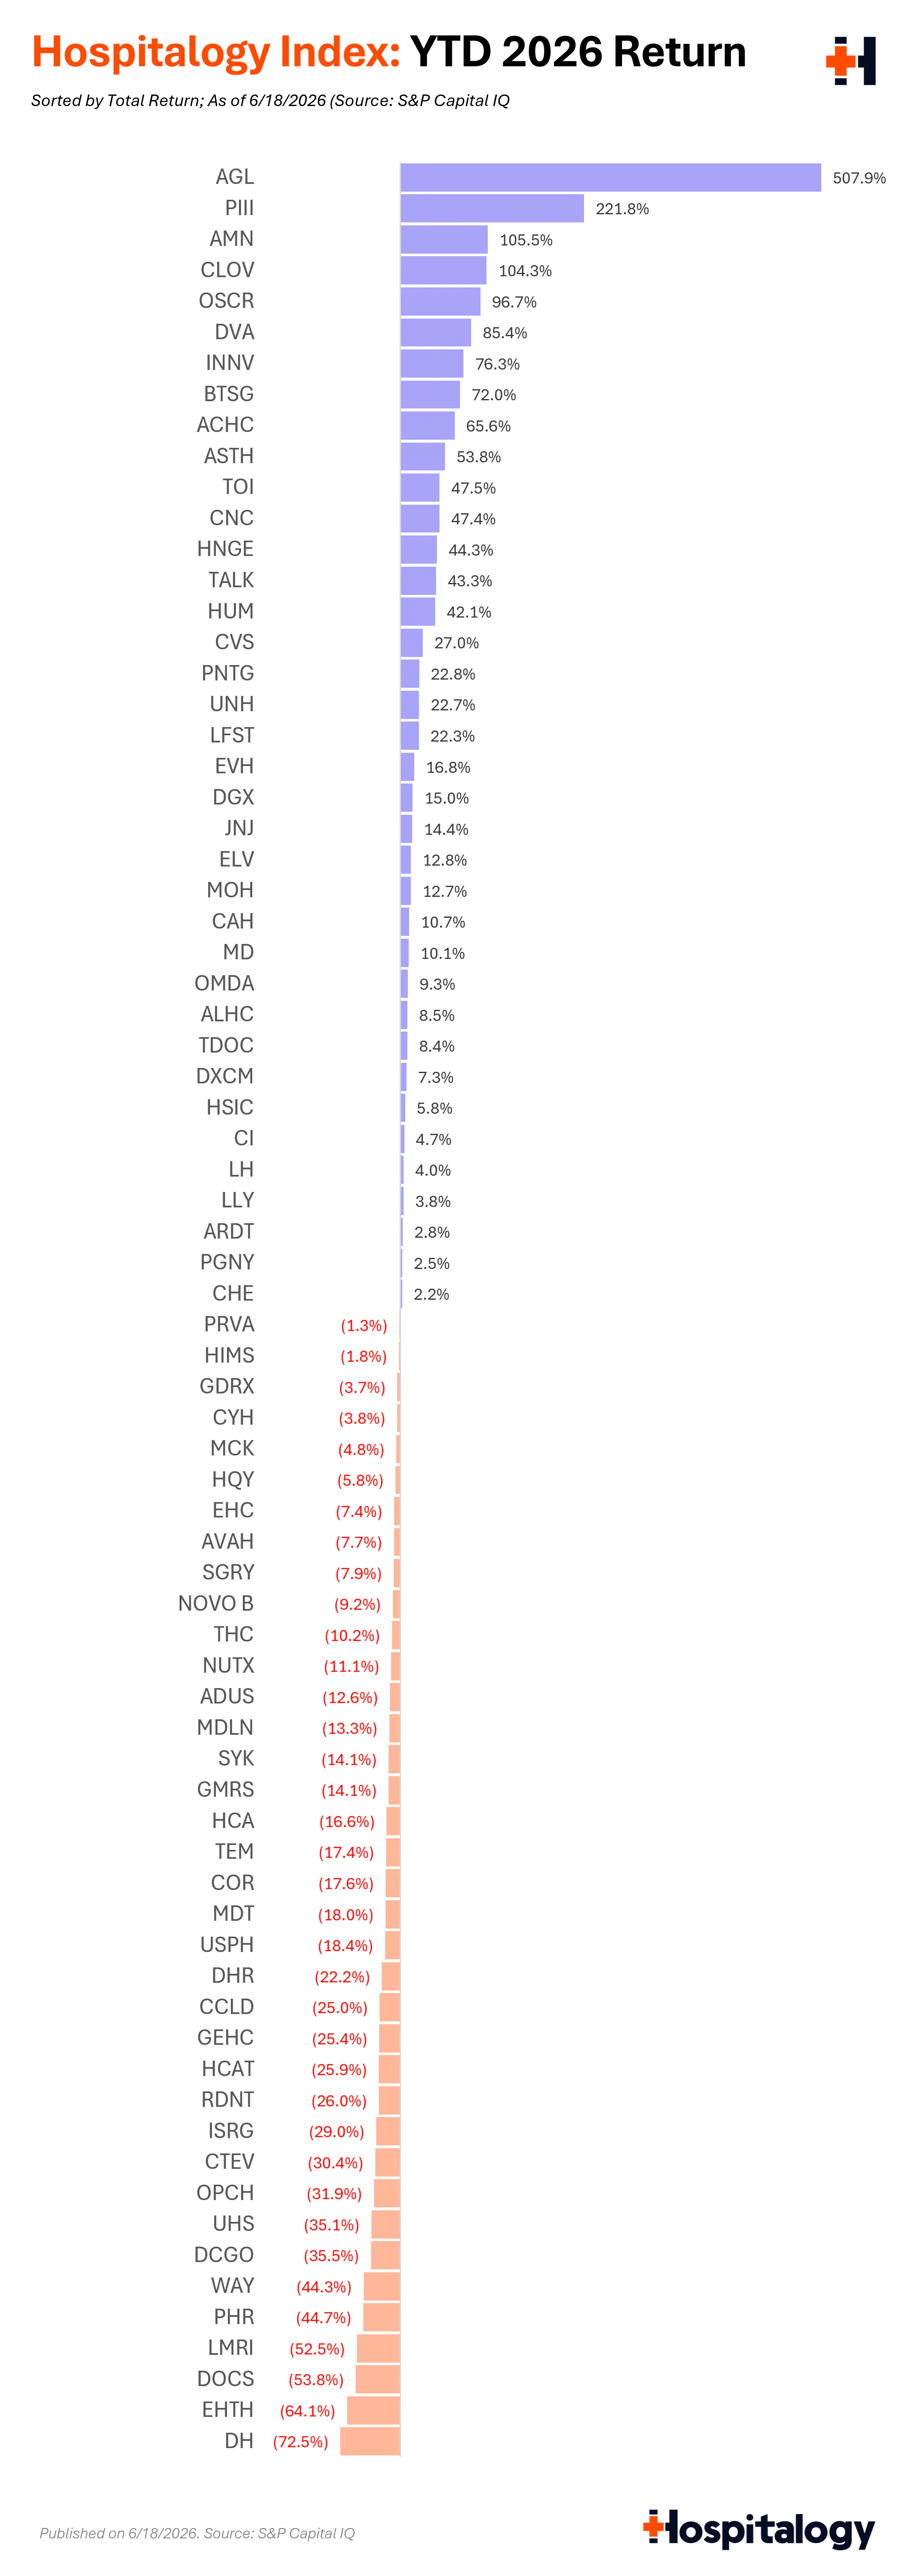
On the bottom end, healthcare SaaS is getting hit hard - Definitive in particular.
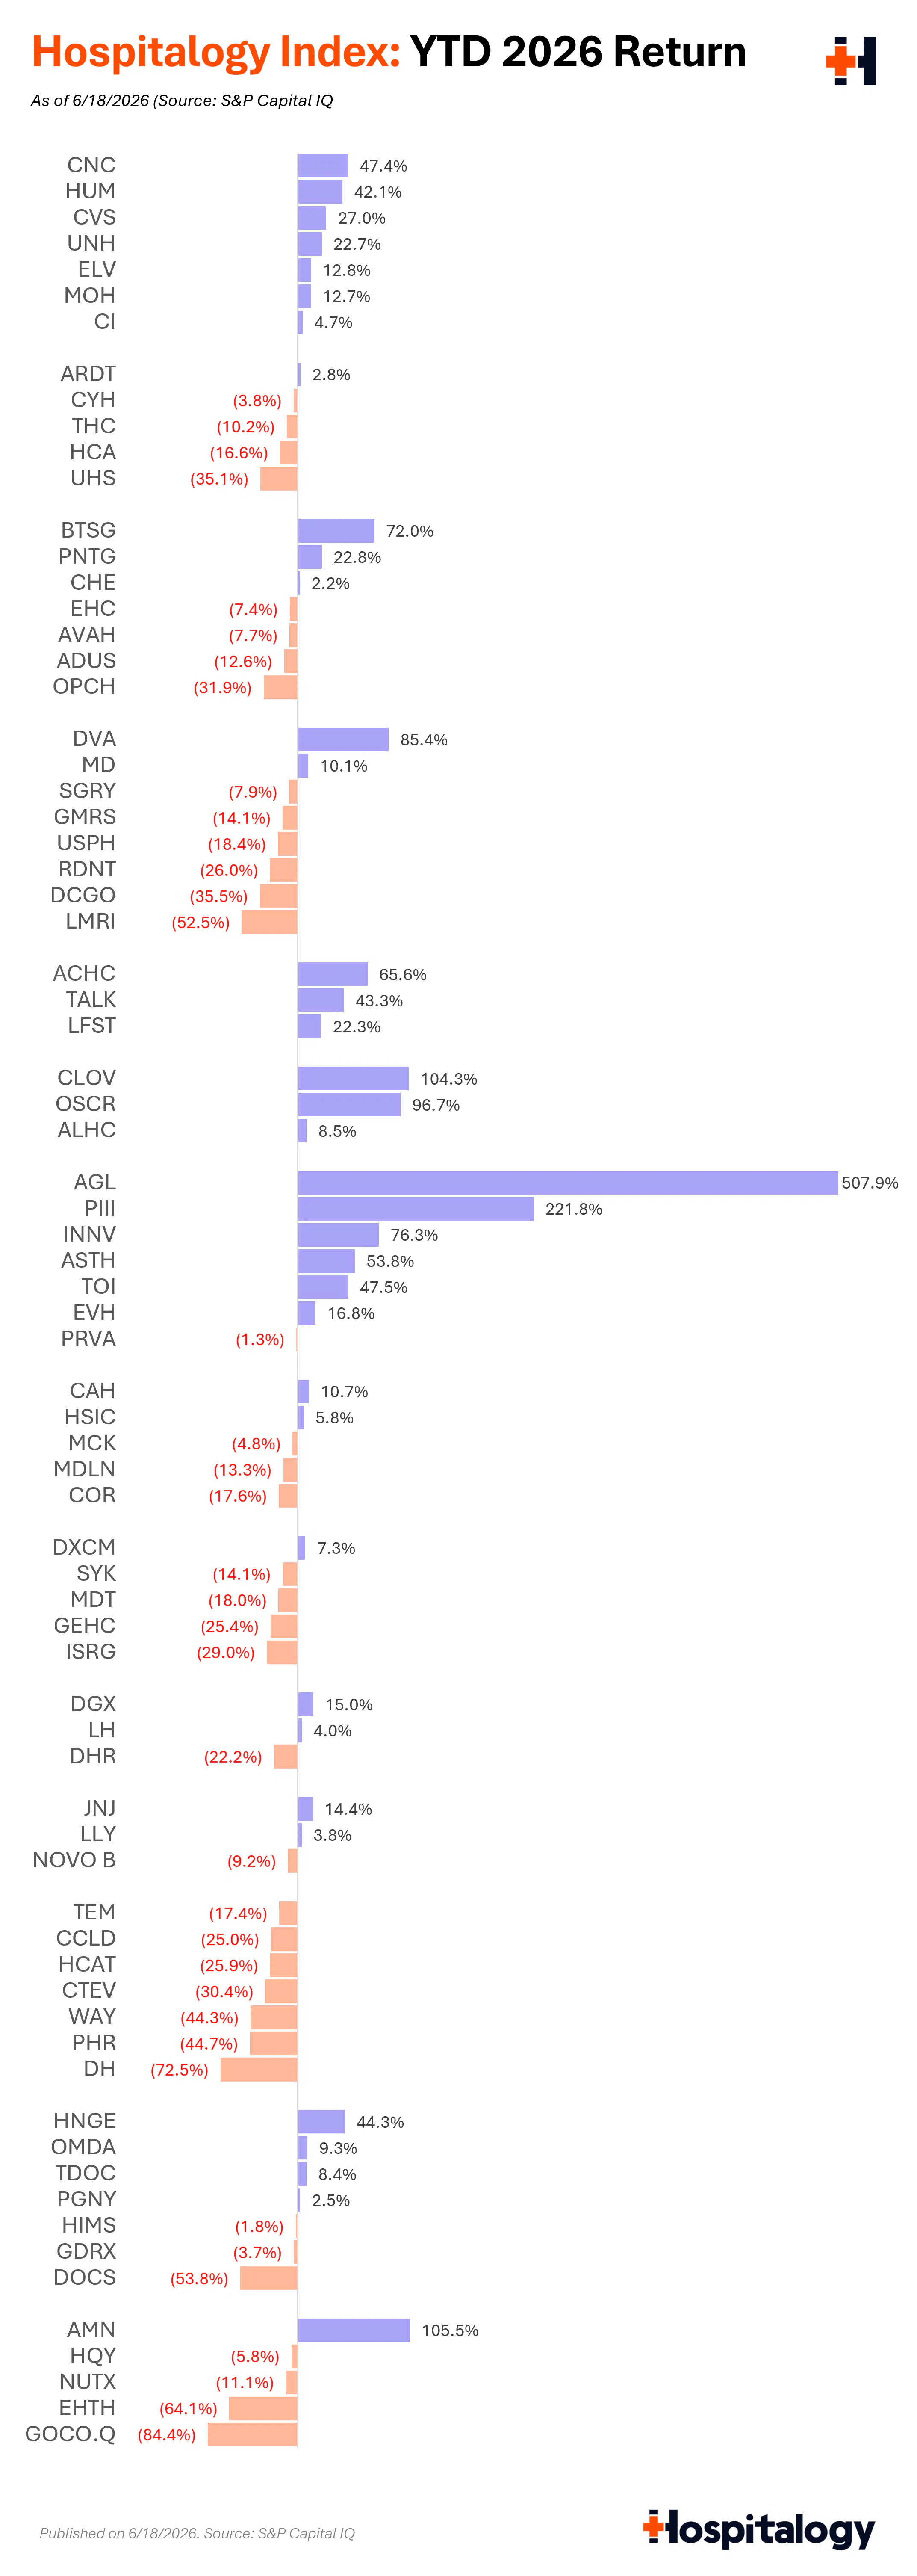
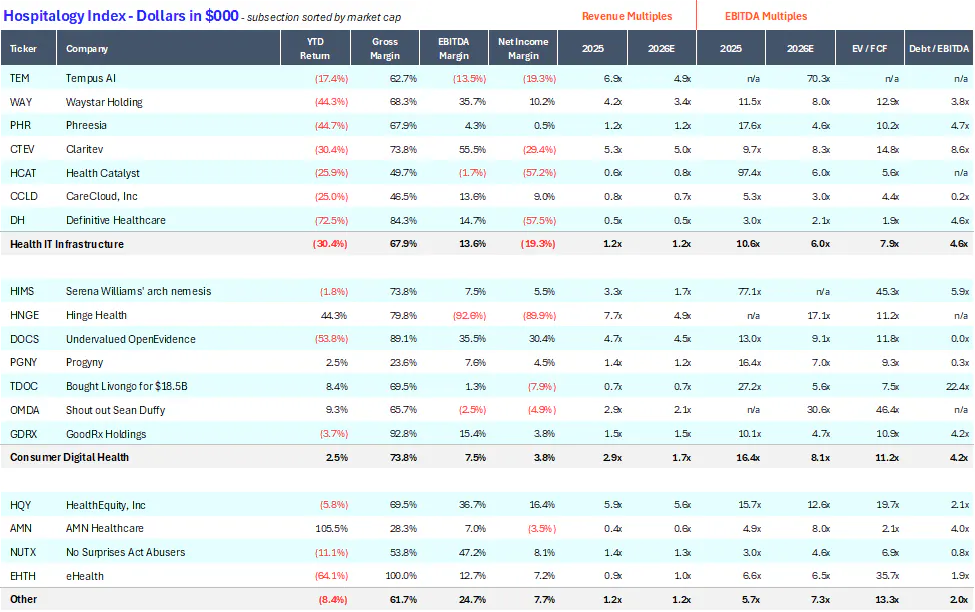
Here’s the index grouped by my arbitrary subsectors:
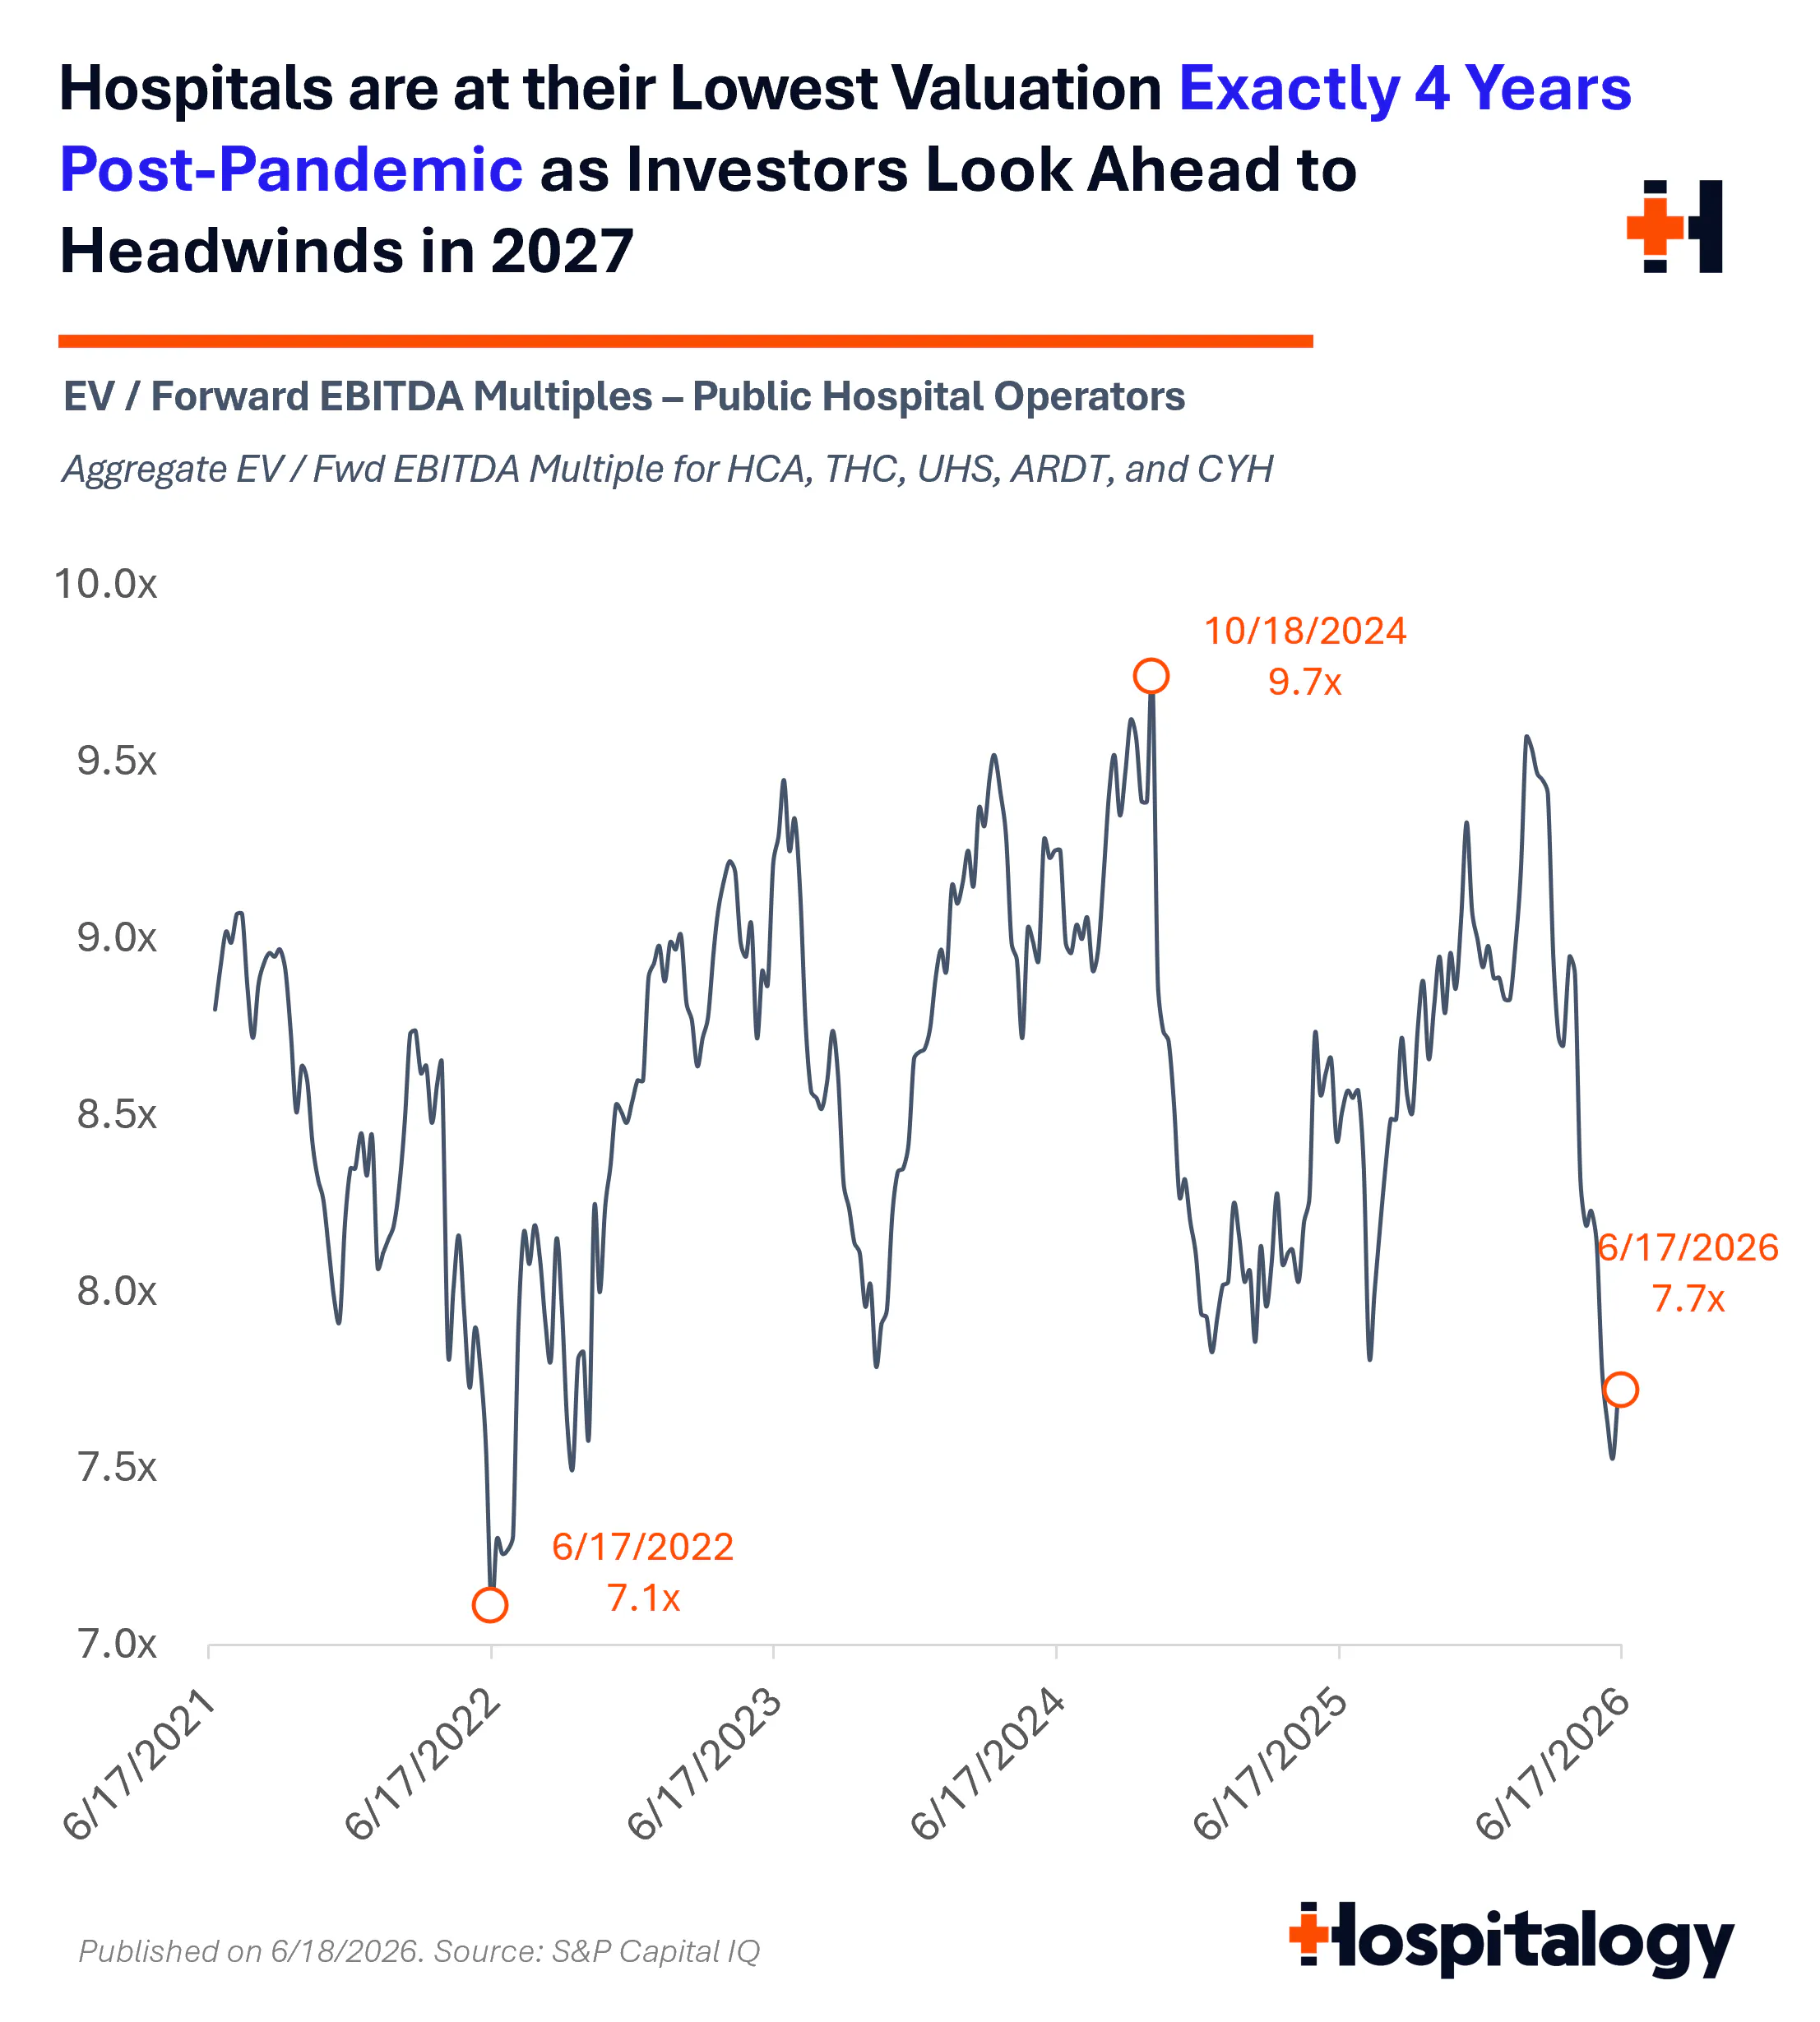
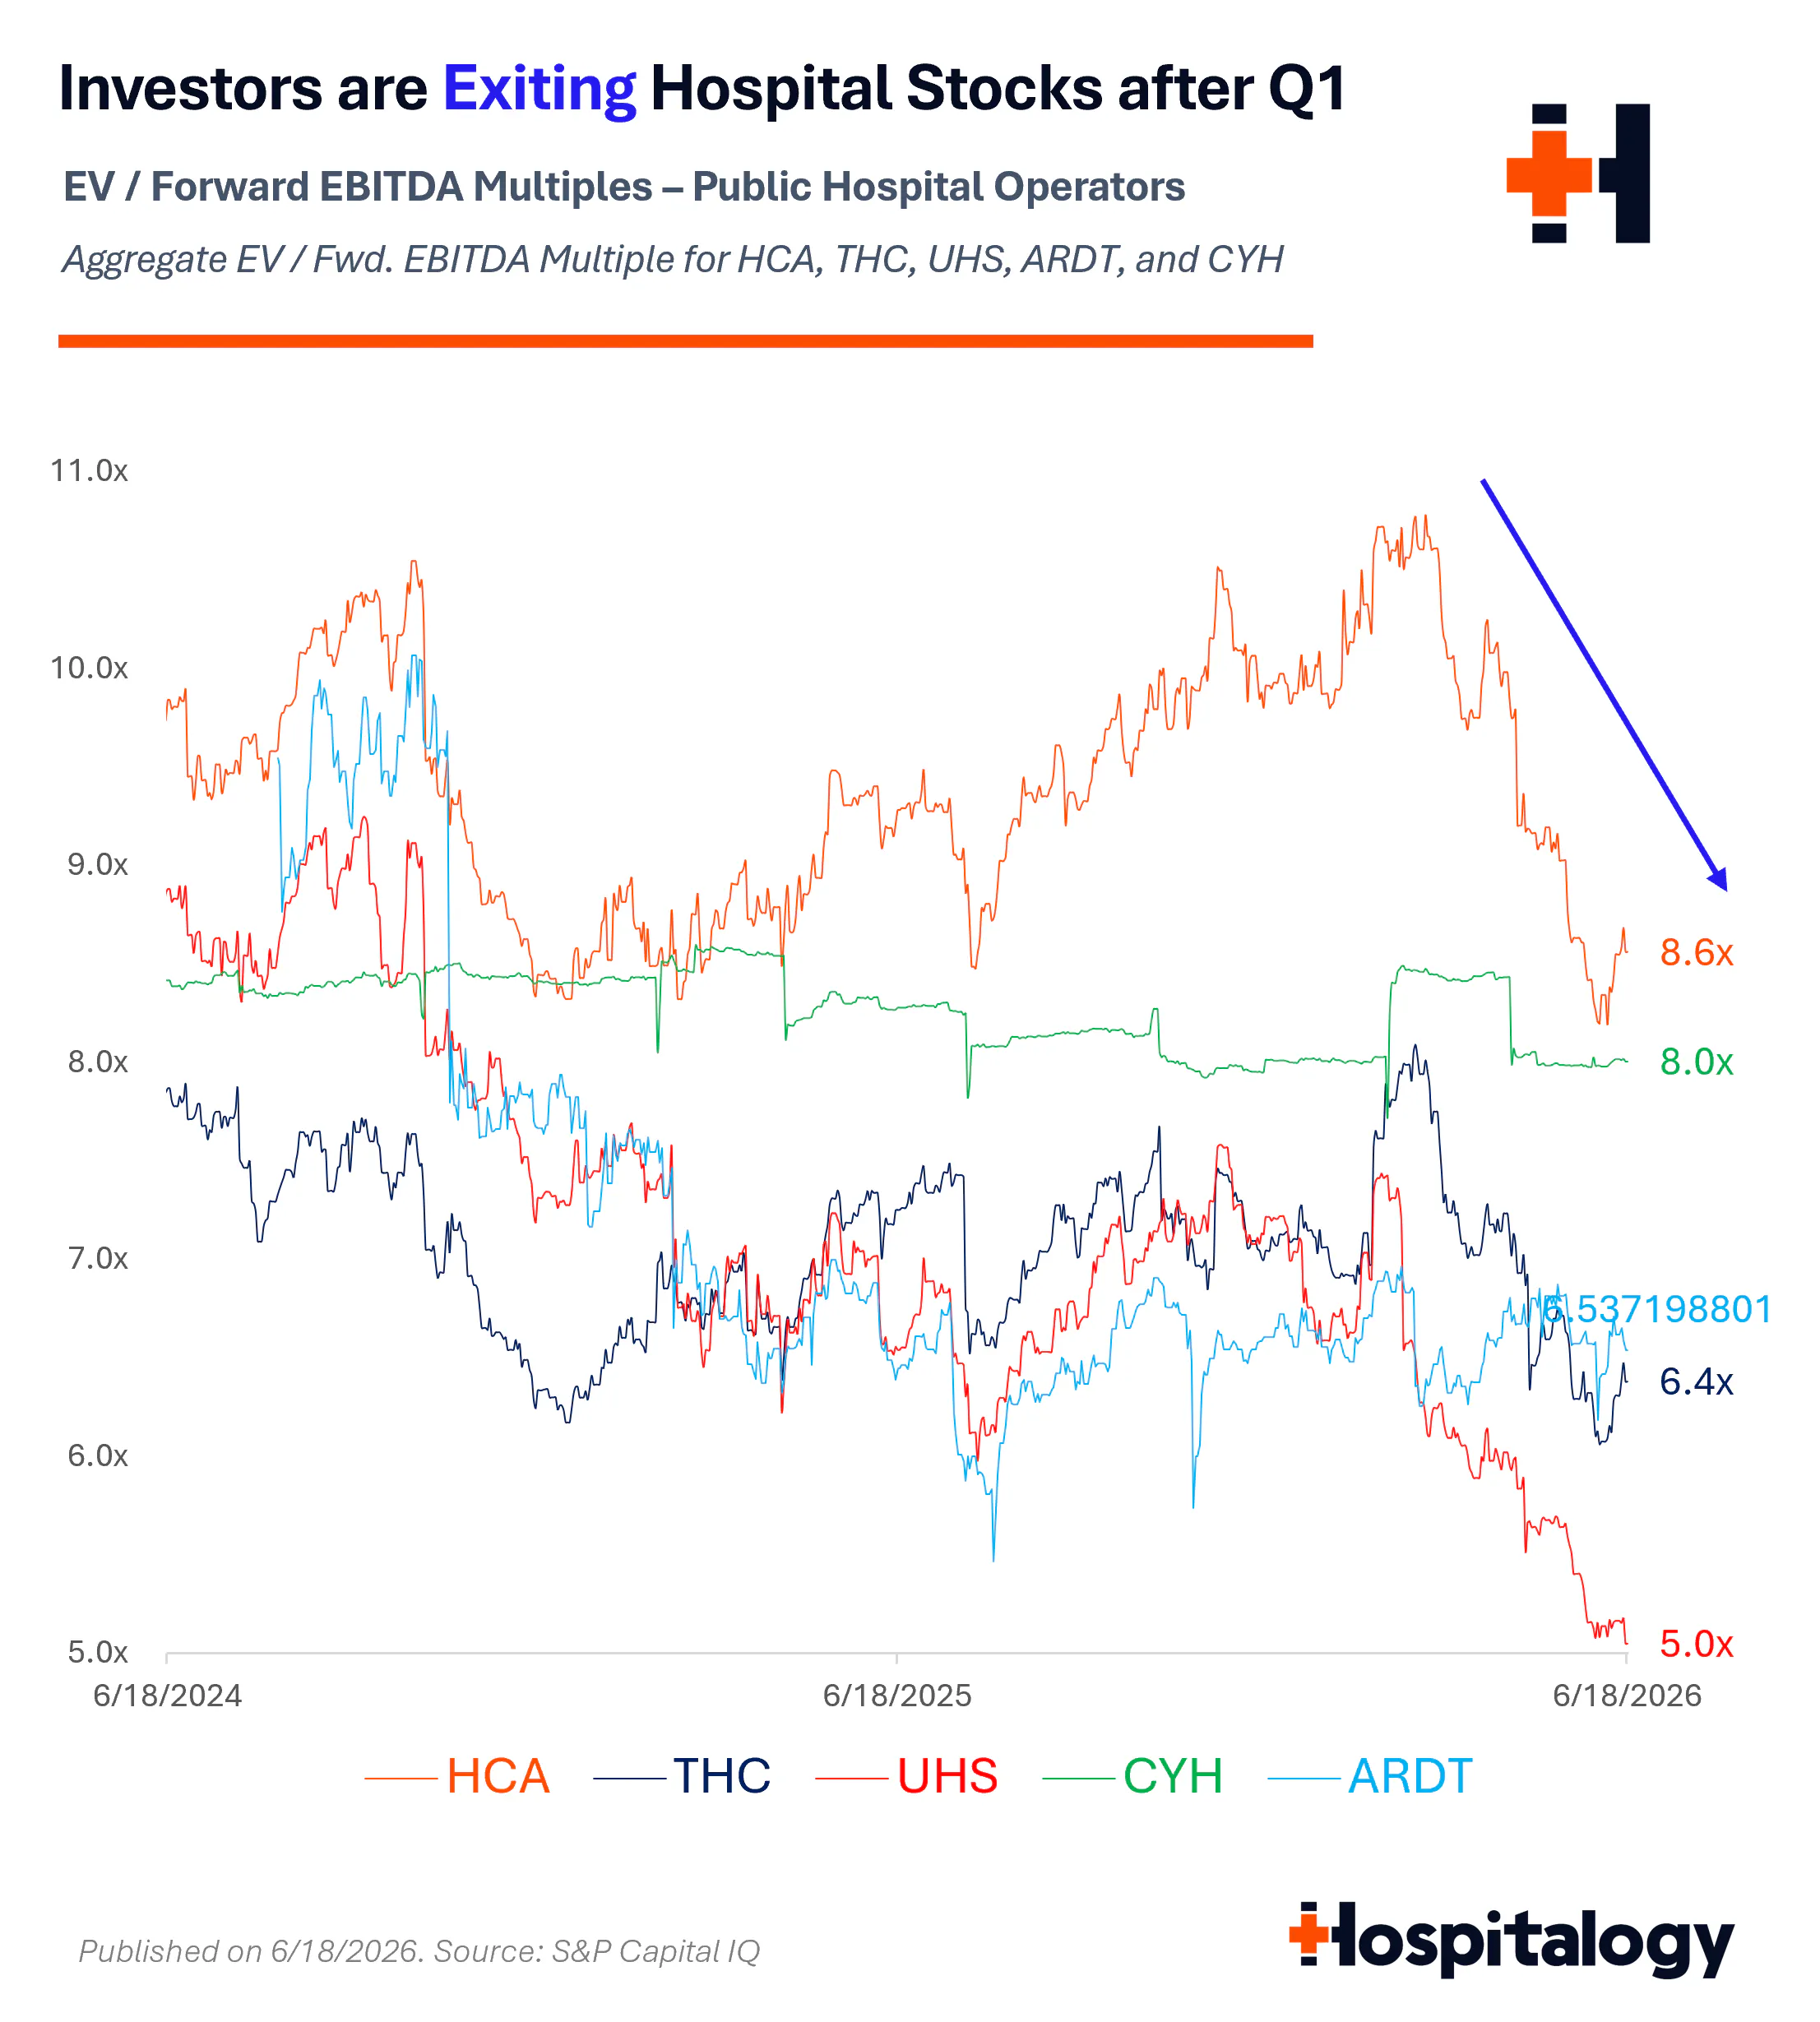
Moving into hospitals, it’s pretty cool / notable to see how the peak hospital operating environment has played out. We’re now past that point - in my humble opinion. Valuations have dropped precipitously over the past few months, and peak valuation across all hospital operators was back in October 2024. Forward EV / EBITDA multiples have declined since then. Still, it’s interesting to see how cyclical the multiples have acted over the past 3 years. Look at that!
I also wanted to dive into each specific public hospital operator’s multiple. Was a particular player dragging the rest of them down?
More or less, we’ve seen a broad selloff since Q1 2026 of hospital names. Since the market is forward looking and these are forward expressions of company valuation, and given the managed care rebound happening in Q1, the move makes sense. But if you take a peek back at the above aggregate chart, hospital valuations are near a 5-year low. Are things THAT bad? Investors don’t like uncertainty, and there sure is a lot between ability to achieve and implement AI investment figures, cost restructuring, and preparation for 2027 headwinds.
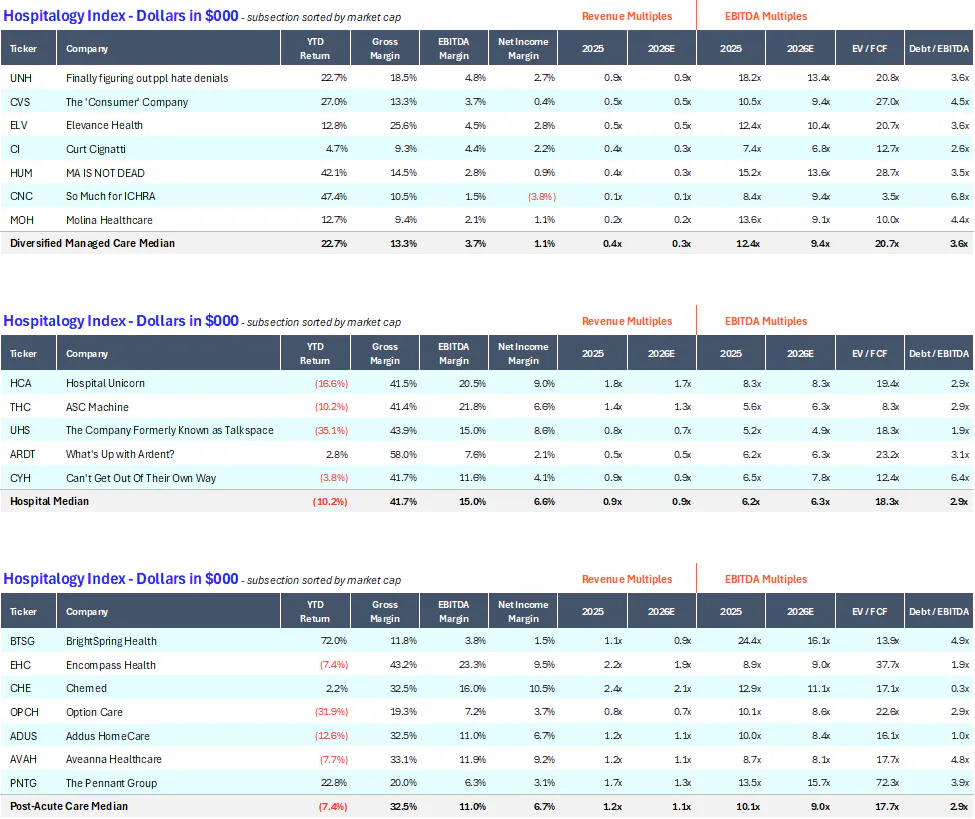
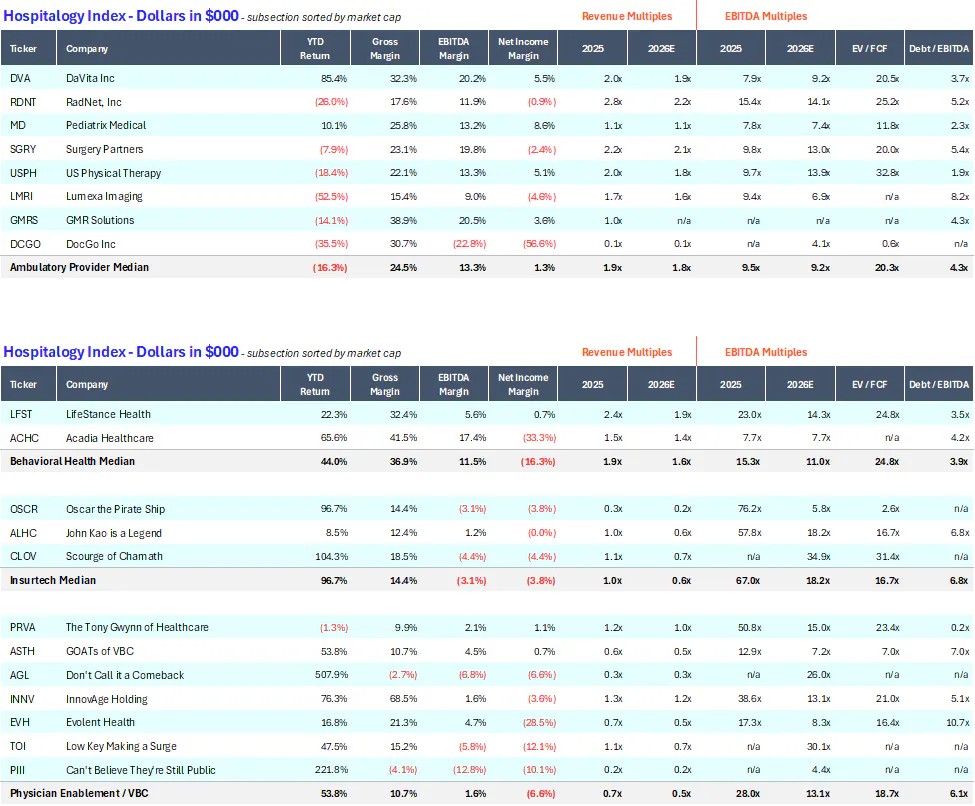
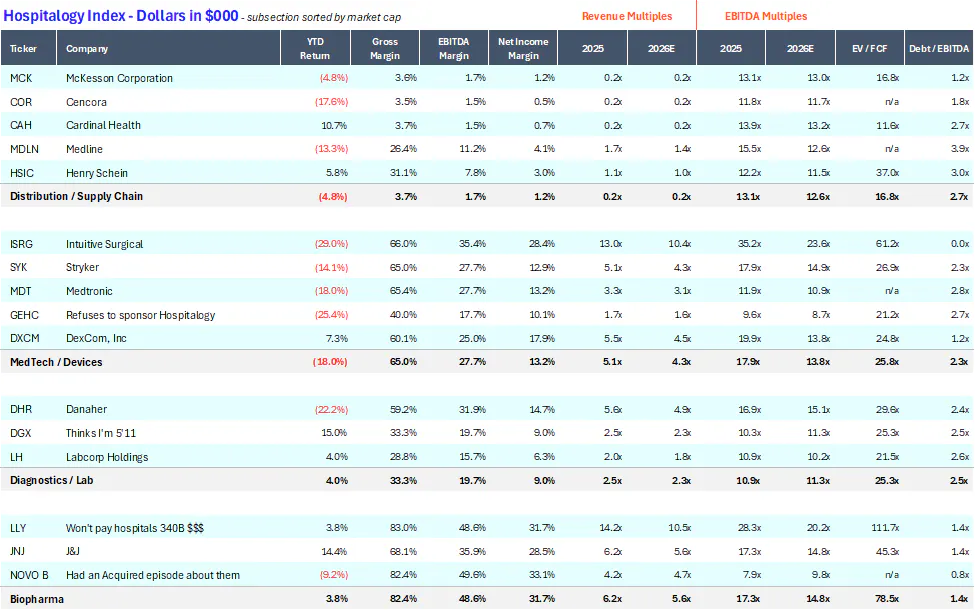
Finally, here is a breakdown of the Hospitalogy Index by sector, starting with Managed Care and moving down from there. I even threw in a few Easter eggs. See if you can spot ‘em.
HOSPITALOGY AI RETREAT UPDATE
Save your seat: Hospitalogy AI RetreatCopy anchor linkCopied
There is nothing noisier in healthcare right now than the clown fiesta happening around AI and technological transformation.
I wrote that in the retreat description, and I meant every word. Health system executives deserve a real conversation around AI. The Hospitalogy AI Retreat is built for exactly that.
100 seats. Application-based. VP+ average seniority. No exhibit halls. Chatham House Rules. Three days at the JW Marriott Desert Ridge in Phoenix (yes, there's golf) to go deep on AI strategy, operating model transformation, and what it actually looks like to move your health system forward.
November 1-4, 2026. Seats are filling fast.
If you’re accepted, your travel, accommodations, and most meals are taken care of. See details.
ON YOUR RADAR
- Resource: Primary care is facing serious headwinds — workforce gaps, an aging population, rising costs. Lumeris maps the headwinds and the actionable path forward for health systems and providers in this free report.*
- Read: Ascension’s R1 Dividend: A story with an update: how Ascension (a customer of R1) "became an owner, kept the operation, and still walked away with the money."
- Provocative: The persistent ACA enrollment fraud.
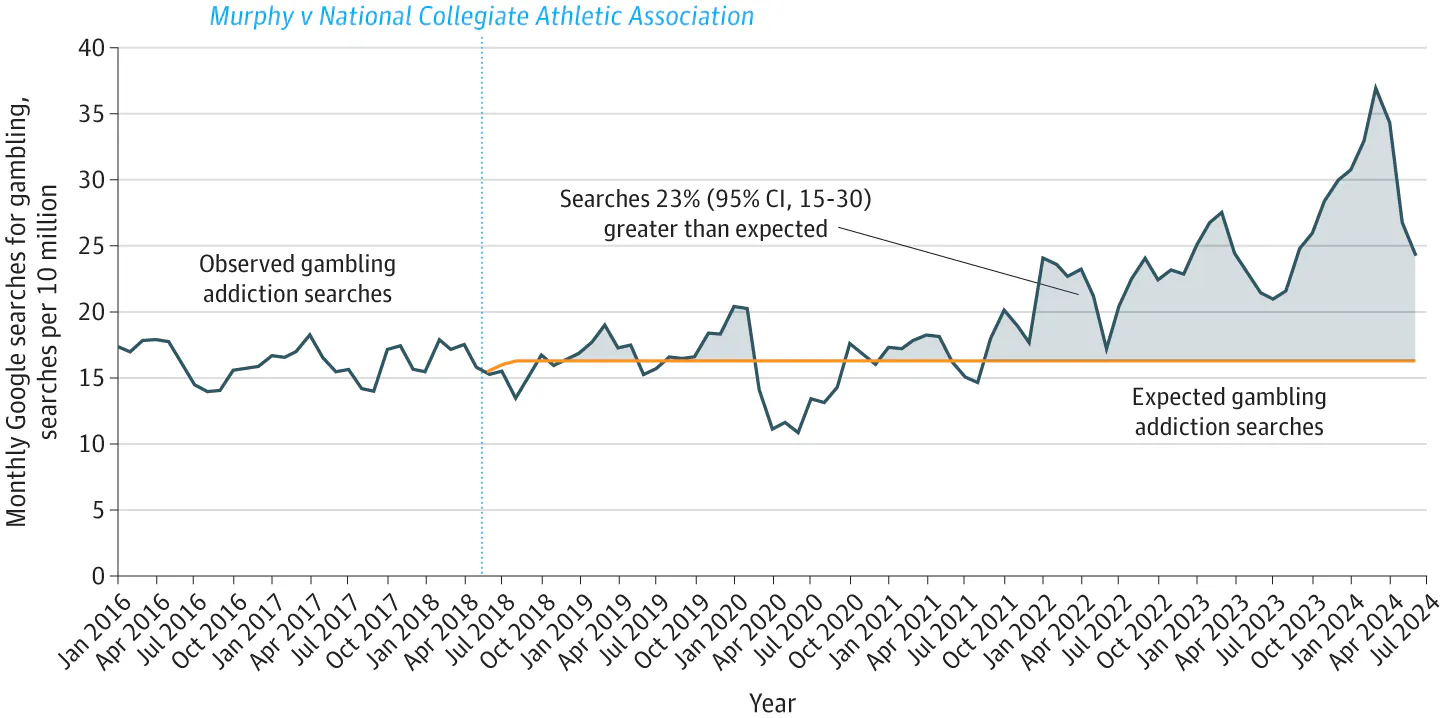
- Clinical Insight: Growing Health Concern Regarding Gambling Addiction in the Age of Sportsbooks.
*This resource is brought to you by one of my brand partners who help make this newsletter possible!
Thanks for the read! Let me know what you thought by replying back to this email.
— Blake