HCA Healthcare's Q3: Strong, Broad-Based Growth...and a Stable Operating Environment Headed into 2025
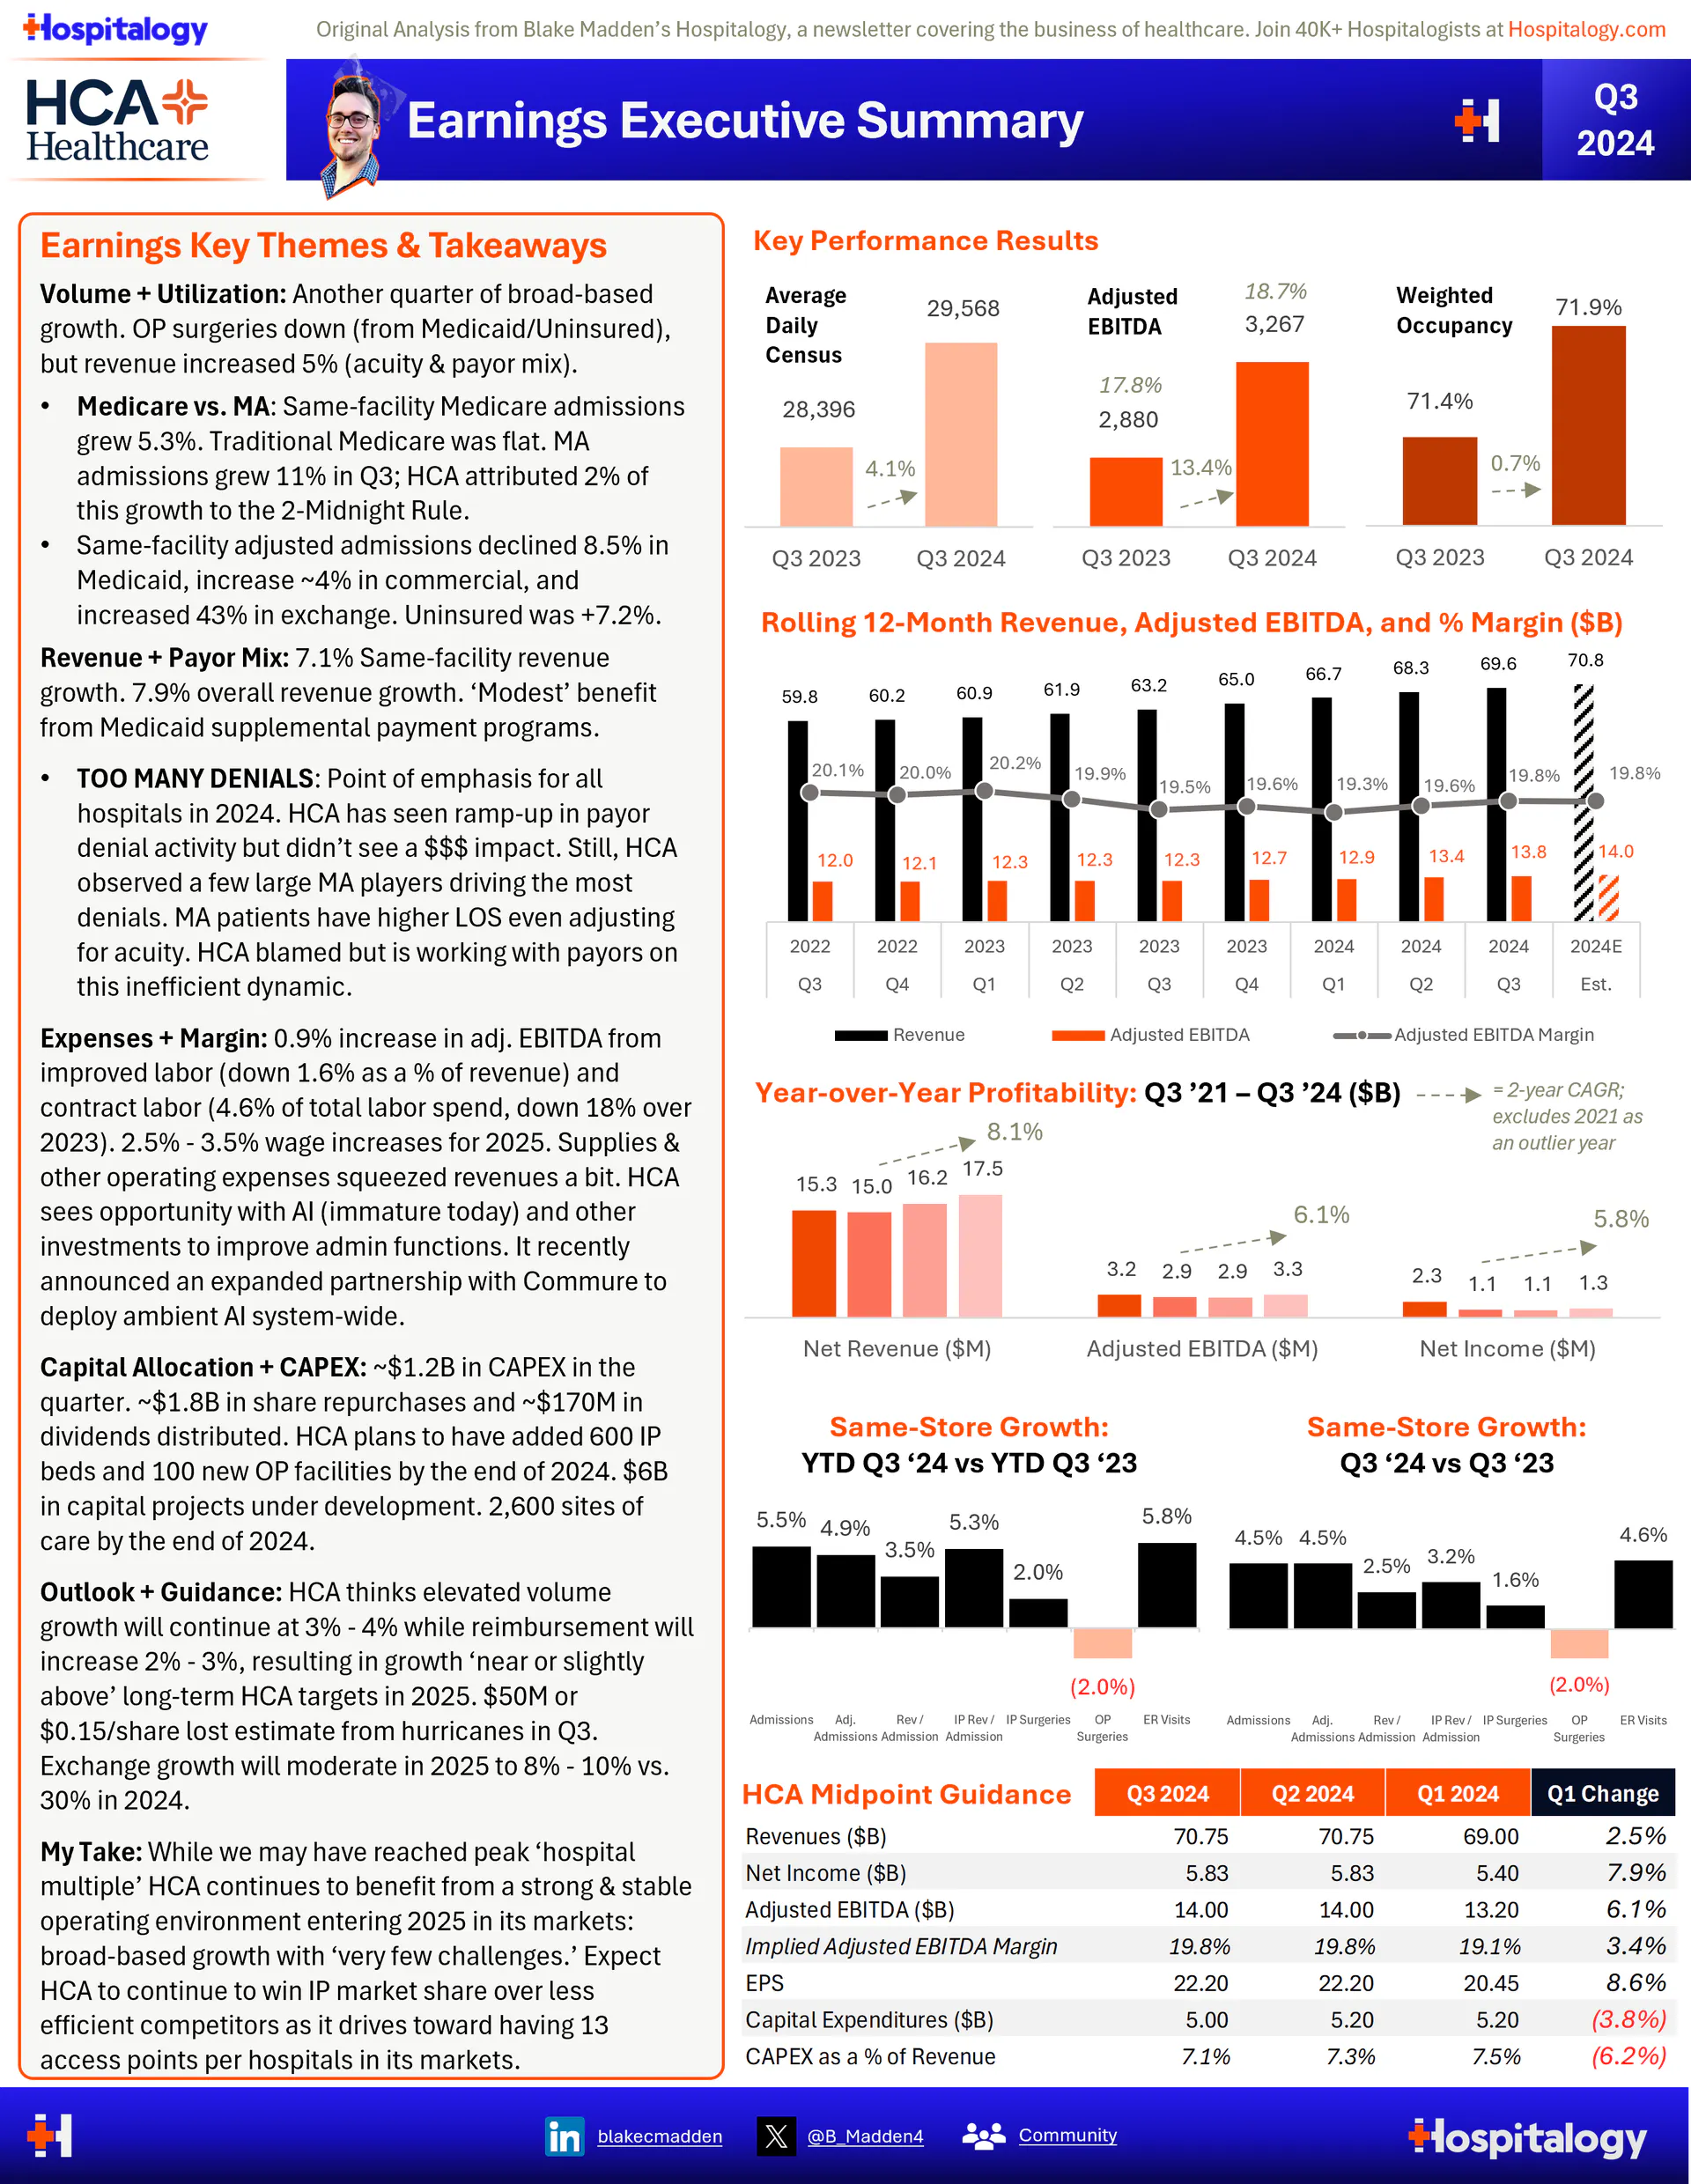
Volume + Utilization:
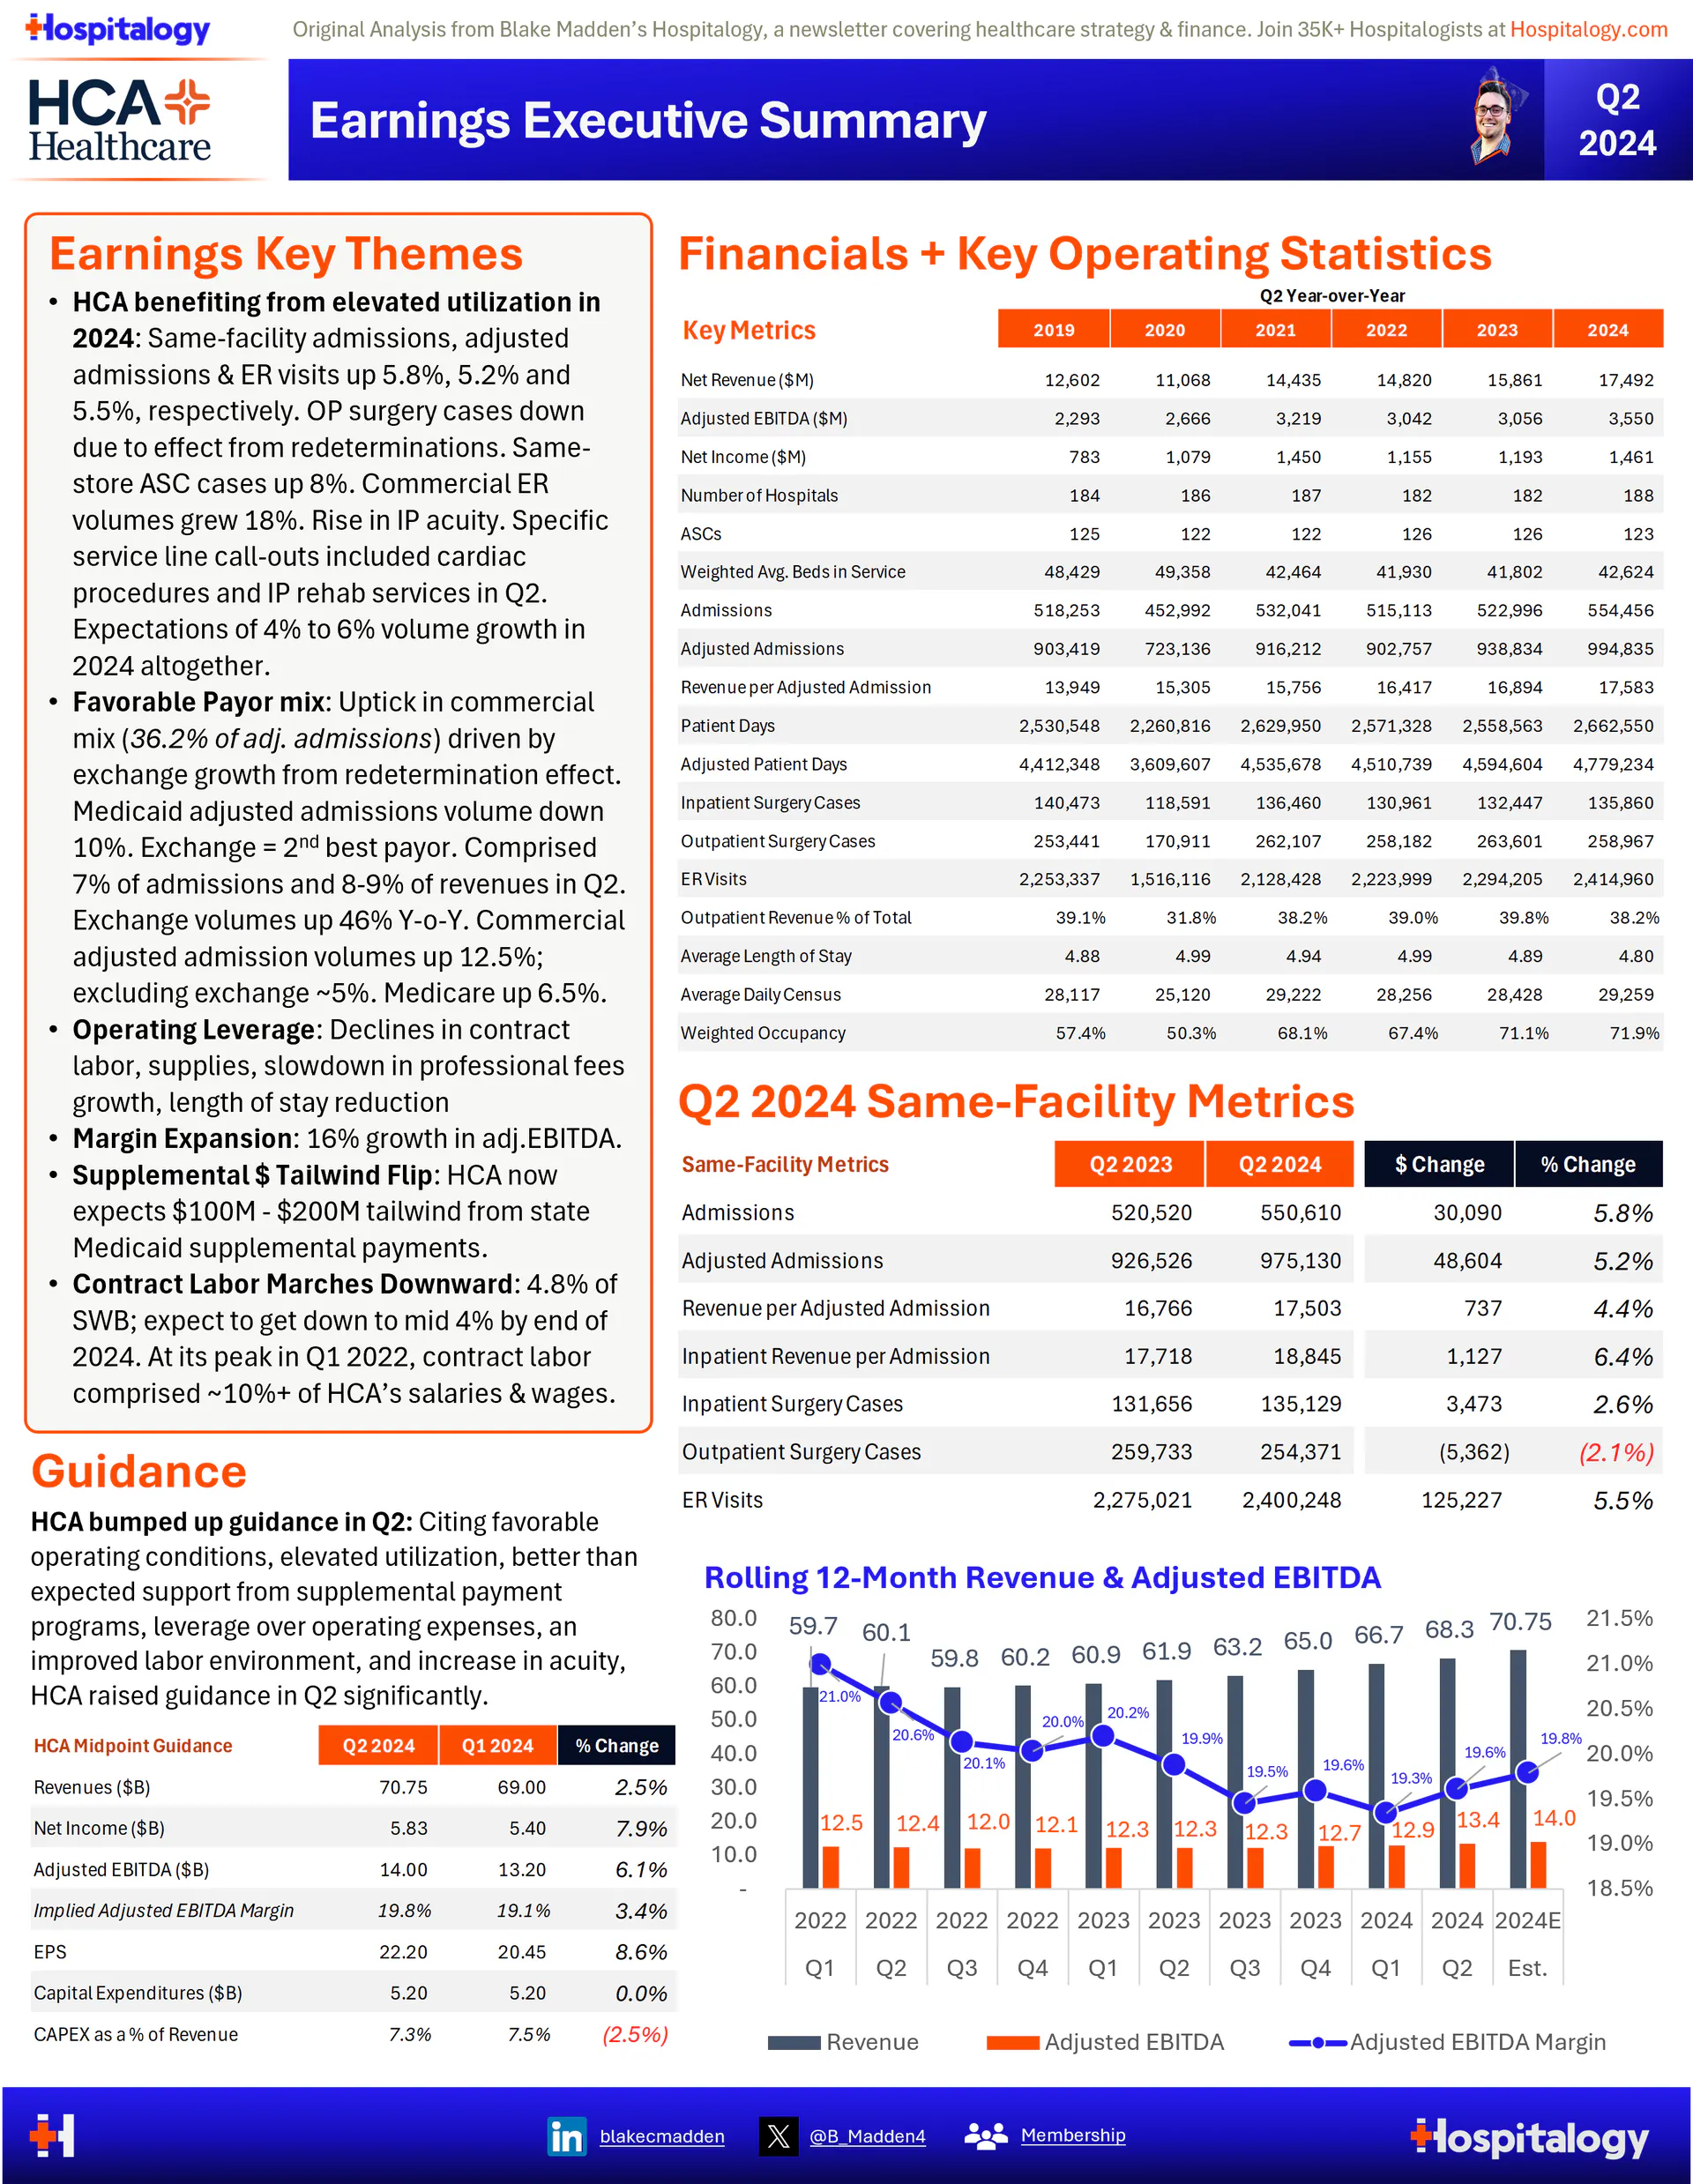
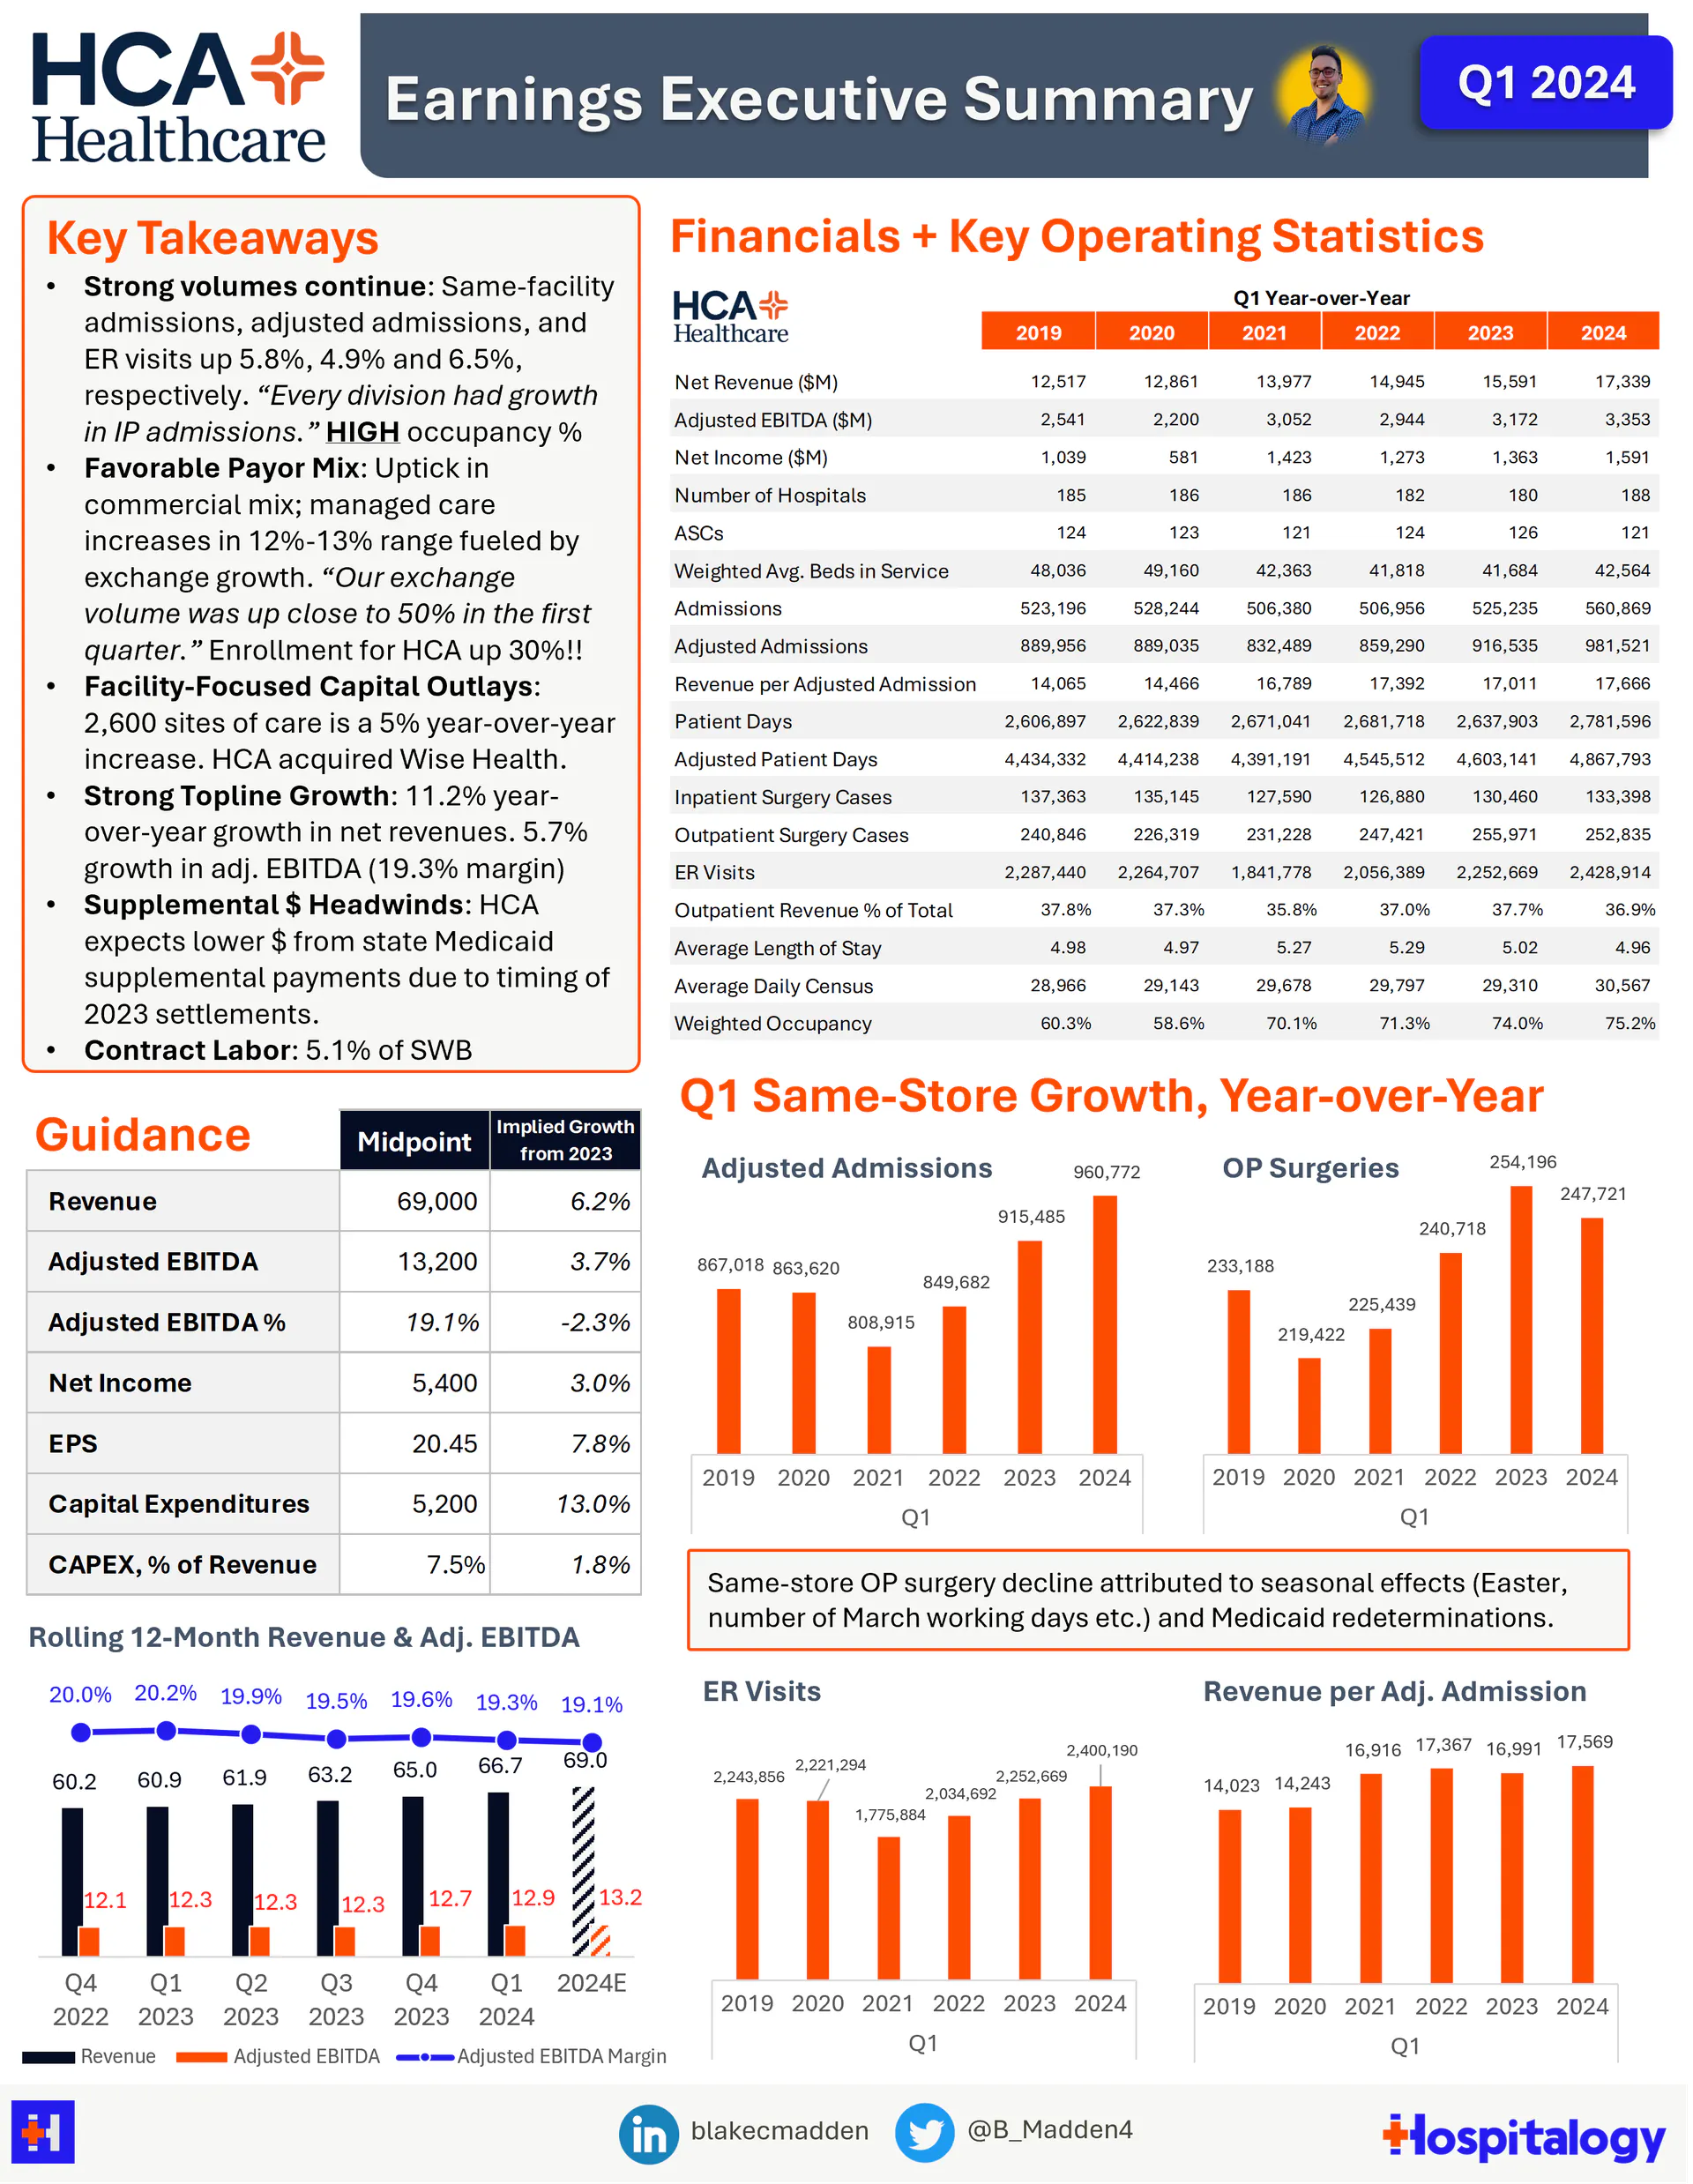
Another quarter of broad-based growth. OP surgeries down (from Medicaid/Uninsured), but revenue increased 5% (acuity & payor mix grew 7% to counteract the decline). HCA specifically called out cardiac procedures, rehab, and obstetrics in prepared remarks on the earnings call itself.
Medicare vs. MA:
Same-facility Medicare admissions grew 5.3%. Traditional Medicare was flat. MA admissionsgrew11%inQ3; HCA attributed 2% of this growth to the 2-Midnight Rule.
Same-facility adjusted admissions declined 8.5% in Medicaid, increased ~4% in commercial, and increased 43% in exchange. Uninsured adjusted admissions increased +7.2%.
Revenue + Payor Mix:
7.1% = Same-facility revenue growth. 7.9% overall revenue growth. ‘Modest’ benefit from Medicaid supplemental payment programs.
TOO MANY DENIALS:
Point of emphasis for all hospitals in 2024. HCA has seen ramp-up in payor denial activity but didn’t see a $$$ impact. Still, HCA observed a few large MA players driving the most denials. MA patients have higher LOS (around 10% higher) even adjusting for acuity. HCA blamed but is working with payors on this inefficient dynamic.
Expenses + Margin:
0.9% increase in adj. EBITDA from improved labor (down 1.6% as a % of revenue) and contract labor (4.6% of total labor spend, down 18% over 2023). 2.5% - 3.5% wage increases for 2025. Supplies & other operating expenses squeezed revenues a bit. HCA sees opportunity with AI (immature today) and other investments to improve admin functions. It recently announced an expanded partnership with Commure to deploy ambient AI system-wide.
Capital Allocation + CAPEX:
~$1.2B in CAPEX in the quarter. ~$1.8B in share repurchases and ~$170M in dividends distributed. HCA plans to have added 600 IP beds and 100 new OP facilities by the end of 2024. $6B in capital projects under development. 2,600 sites of care by the end of 2024.
Outlook + Guidance:
HCA thinks elevated volume growth will continue at 3% - 4% while reimbursement will increase 2% - 3%, resulting in growth ‘near or slightly above’ long-term HCA targets in 2025. $50M or $0.15/share lost estimate from hurricanes in Q3. Exchange growth will moderate in 2025 to 8% - 10% vs. 30% in 2024.
My Take:
While we may have reached peak ‘hospital multiple’ HCA continues to benefit from a strong & stable operating environment entering 2025 in its markets: broad-based growth with ‘very few challenges.’ Expect HCA to continue to win IP market share over less efficient competitors as it drives toward having 13 access points per hospitals in its markets.