Hospital M&A is BACK!
Breaking down the recent mega deals and what it means for the future of health systems
Hospitalogists,
Anthropic released its IPO financials this week so, naturally, in true Hospitalogy fashion, we’re diving into health system M&A instead. And just like Texas after knocking off Ole Miss, health system M&A (and capital markets activity in general) is BACK in a big way. Let’s break it down.
Also, join me on Friday to talk all things physician practice M&A! The more the merrier. It’s an informal session purpose designed for all Hospitalogists.
I’ll be joined by 2 experts (from my old firm, by the way) who have a fascinating thesis on the physician practice management market, so we’ll be talking about their thesis for why health systems are potentially emerging as a strategic buyer of PPMs and why the future of PPM M&A may be regional in nature.
Register here - anyone who is subscribed to this newsletter can join!
BLAKE'S BREAKDOWN
The Health System Q4 Deal Rush (pun totally intended). Two-Minute Drill Edition.Copy anchor linkCopied
It's the 4th quarter, and health system M&A, all of a sudden, is running the two-minute drill with a slew of deals to start things off.
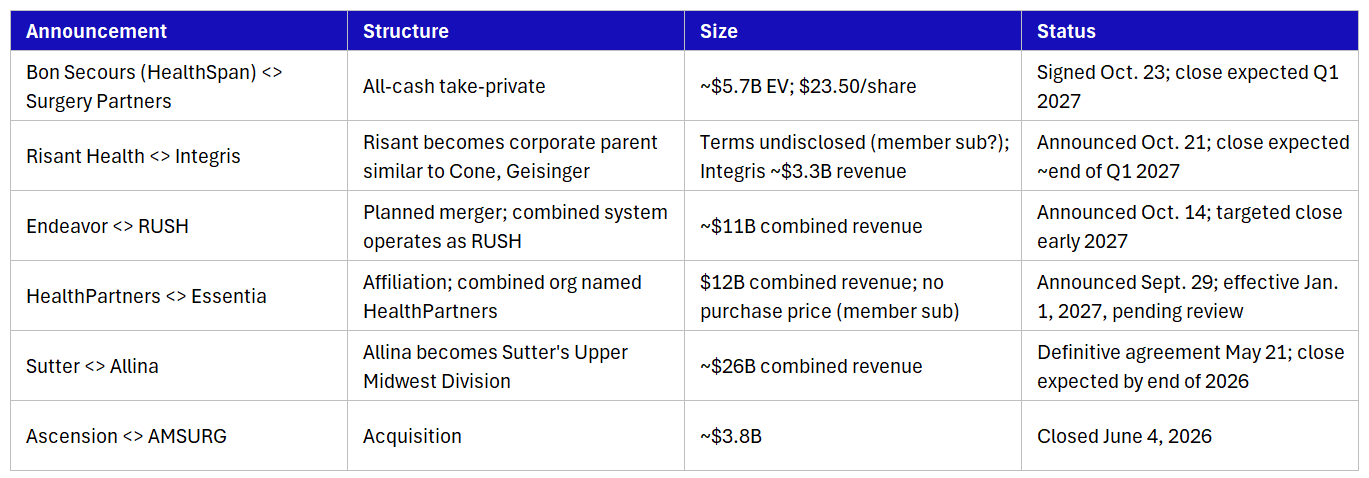
Since Sept. 29 (alright, technically not Q4 but come on), the following has been announced:
- HealthPartners and Essentia agreed to combine,
- Endeavor and RUSH announced plans to merge under the RUSH name
- Integris signed on as Risant's 3rd system, and
- a Bon Secours Mercy Health affiliate (HealthSpan) agreed to take Surgery Partners private at a ~$5.7B enterprise value.
Meanwhile, Sutter and Allina are still aiming to close by the end of the year on top of Erlanger-Prisma and Intermountain-Advent in Denver announcing deals in Q3.
Then, over on the services side and adjacent to health system activity, Option Care, CenterWell's clinic JV, American Oncology Network, Summit Health's New Jersey business and another chunk of BioReference all agreed to deals in the same 3-week stretch.
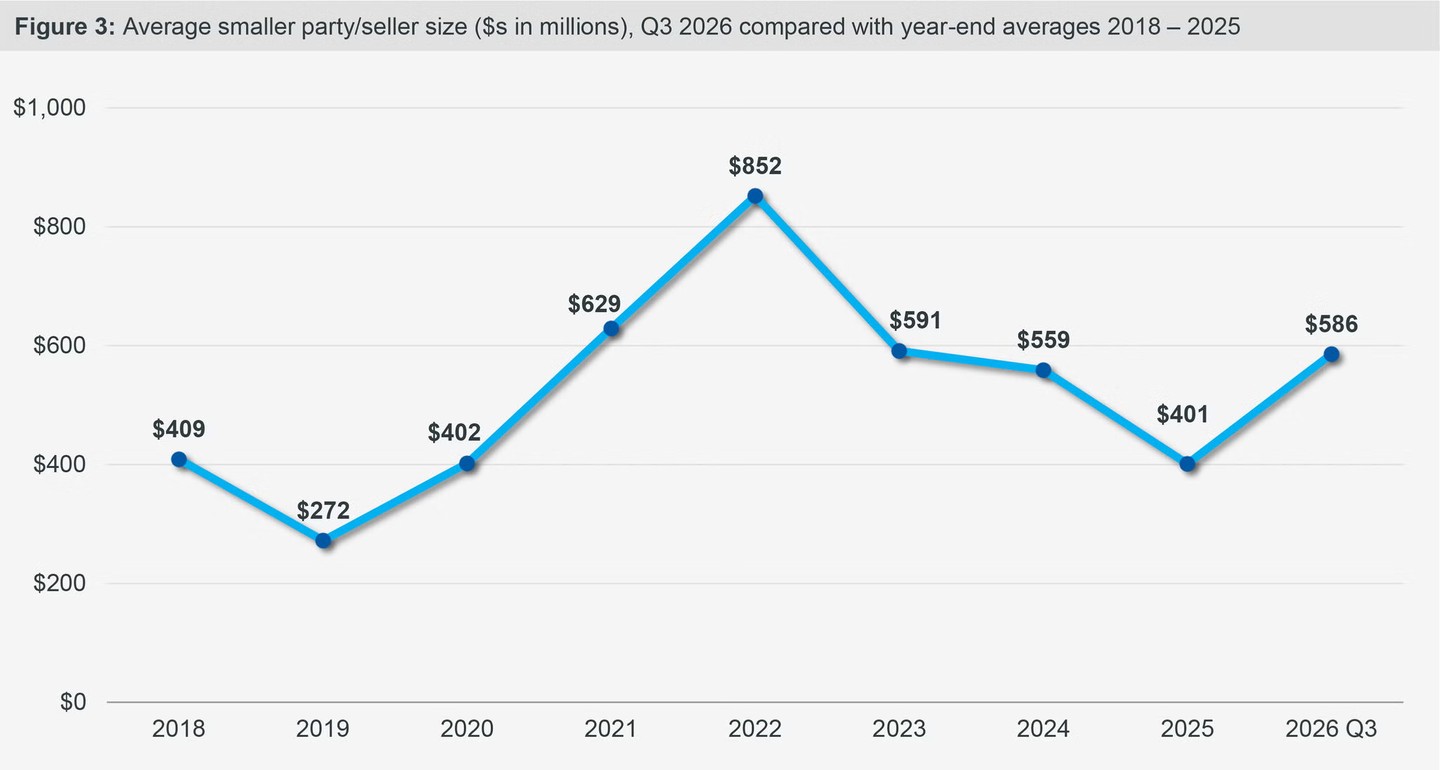
Kaufman Hall counted 16 hospital and health system deals in Q3, bringing 2026 to 56 through 3 quarters, already ahead of all of 2025 (46), which was the slowest year since tracking began in 2011. Plus, deals are getting bigger: the average Q3 seller brought ~$586M in revenue, up from ~$401M a year earlier.
Stated otherwise, we are so back…for now.
So today is more of a factual breakdown and roundup: every deal, the terms, and where it stands, with context. Then, shortly thereafter, Part 2 will be an essay on what it all means and some fun thoughts from yours truly.
Let's break it down.
Health system deals - a breakdownCopy anchor linkCopied
Bon Secours Mercy Health takes Surgery Partners private at $5.7B.Copy anchor linkCopied
HealthSpan Partners, a Bon Secours Mercy Health affiliate, agreed to buy Surgery Partners for $23.50 a share in cash, an enterprise value of ~$5.7B (8-K, Ex. 99.1). Reuters put the premium at 49% to the prior close (Reuters via KSL). Surgery Partners signed the merger agreement Oct. 23 and announced it Oct. 26 (8-K; Business Wire).
- Footprint: 200+ locations in 30 states and ~5,000 affiliated physicians. Surgery Partners stays secular and keeps its name, brand and headquarters.
- Bain Capital: owns ~39% of shares, rolls its stake into the acquiring entity instead of cashing out, signed a voting agreement, and stays a significant partner (Kirkland).
- Financing: cash on hand plus new debt, with Jefferies as sole initial underwriter on committed financing. No financing condition; BSMH guarantees the buyer's obligations. BSMH has also been receiving annual dividends from its investment in Ensemble Health Partners which has massively bolstered its balance sheet for this acquisition. Talk about a competitive advantage!
- Process and timing: negotiated by a special committee of independent directors; no-shop; ~$109M company termination fee; needs a majority of outstanding shares and a majority of votes cast by disinterested stockholders, plus HSR clearance. Outside date July 23, 2027; close expected Q1 2027.
- Context: Bain made a non-binding offer of $25.75 a share in January 2025. Its special committee ended that process in June 2025, concluding its standalone plan was worth more. I guess a sale was in the cards all along!!
Risant adds Integris as its 3rd systemCopy anchor linkCopied
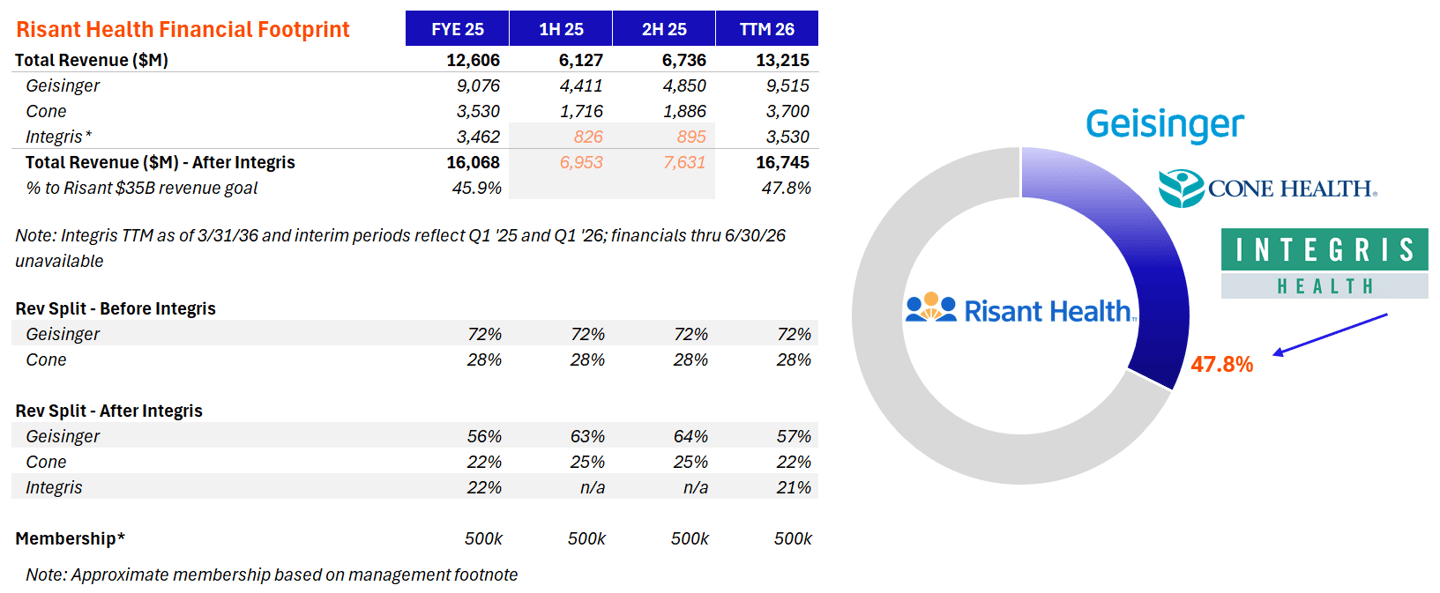
Integris Health signed a definitive agreement to join Risant Health, announced Oct. 21 (release). Risant, the nonprofit Kaiser Permanente created to acquire regional systems, becomes Integris' corporate parent.
- Scale: 10 acute and 10 specialty hospitals, 13,000 employees, and $3.3B in operating revenue for the fiscal year ended June 30, 2025.
- Governance: In typical Risant fashion, Integris keeps its name, brand, medical staff, leadership, governing boards and Oklahoma City headquarters.
- Financial backdrop: Integris expects more than $130M in 2026 revenue losses tied to Medicare and Medicaid cuts in HR-1 plus planned service line and staff reductions. It has run at an operating loss for the past 2 years (Healthcare Dive).
- Capital: no dollar commitment specific to Integris. Risant plans generally to invest ~$5B across about half a dozen regional systems. The departure from explicitly stated planned capital commitments is interesting given what Risant promised Cone and Geisinger on that front:
- Risant will make a minimum of $2 billion available to Geisinger — inclusive of any Geisinger internally generated and Risant funds — through Dec. 31, 2028, to support hospital, ambulatory facility, technology and other strategic and routine capital.
- Risant will make a minimum of $1 billion available to Cone — inclusive of any Cone internally generated and Risant funds — through the fifth anniversary of the closing date. The funds will be earmarked for investments in facilities, health equity and other capital projects. Risant will also ensure up to $400 million in funding during the capital commitment period to support Cone’s transition, including the initial implementation of the value-based platform. Risant will also ensure up to $300 million in funding in the 10 years following the closing date to support Cone’s growth opportunities.
- Kaiser Foundation Hospitals designated up to $5 billion to support core Risant capabilities, technologies, tools and future investments. Kaiser will invest at least $400 million for a five-year period after Risant’s launch, inclusive of funds generated by Risant.
- Timing: interim Risant CEO Dale Maxwell expects completion around the end of Q1 2027
- Context: Risant closed Geisinger on March 31, 2024 and Cone Health on Dec. 1, 2024.
- Related: Why Kaiser Permanente Formed Risant Health
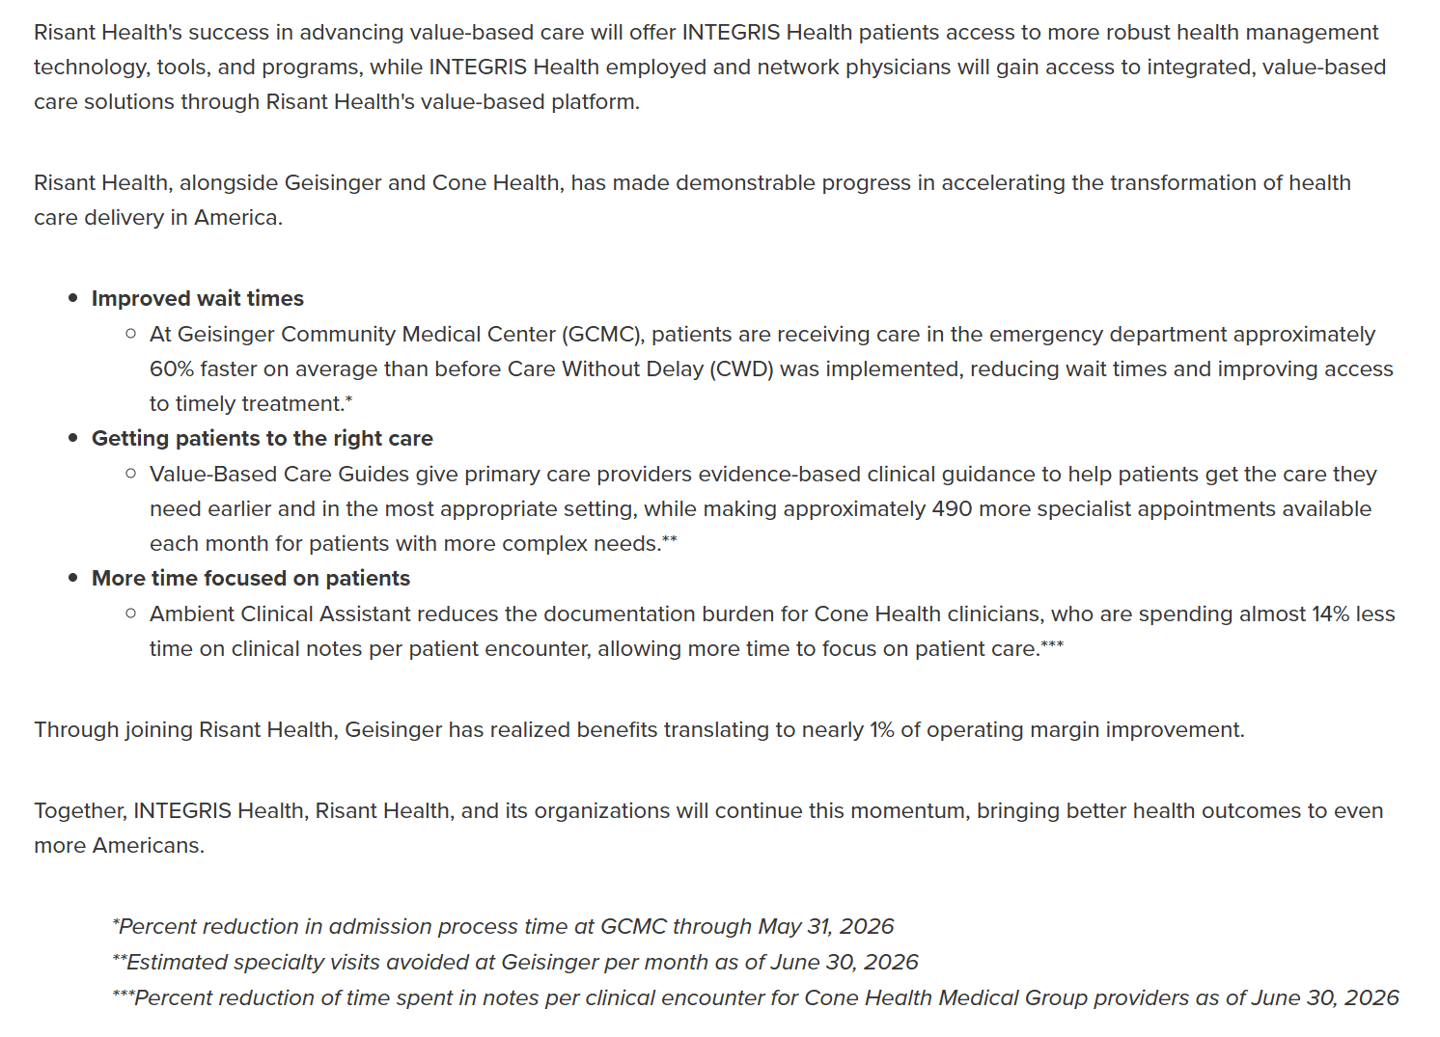
Also, these notes below on Risant’s progress to date were interesting - faster ED and admissions throughput, expanded access (scheduling and additional care team member support), and further ambient deployment. If anyone knows the vendors or initiatives attached to these KPIs I’m all ears!
Endeavor and RUSH plan to combine under the Rush nameCopy anchor linkCopied
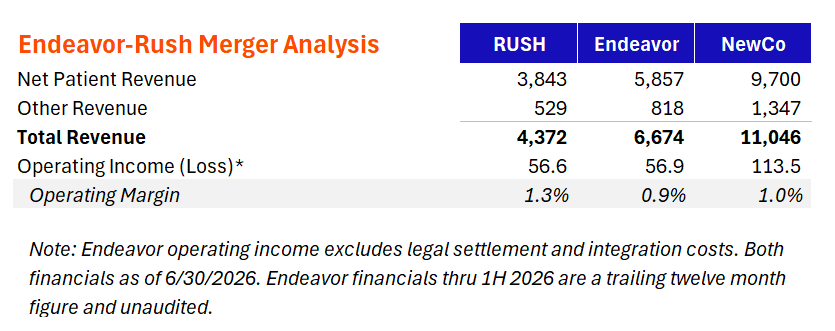
Rush University System for Health and Endeavor Health announced plans to merge on Oct. 14, creating a 12-hospital system with 400+ care sites and 46k+ employees and clinicians and 2 million patients.
- Revenue: over $11B in annual operating revenue through unaudited 6/30/2026 financials (this is the most current figure available). Endeavor is the larger partner: ~$6.7B in TTM 2026 revenue vs. Rush's ~$4.4B through the 12 months ended June 30, 2026.
- Governance: Endeavor CEO J.P. Gallagher becomes president and CEO of the combined system; Rush CEO Omar Lateef becomes CEO Emeritus and strategic advisor. A 20-person board splits seats evenly, with a chair from the Rush side. Brand will operate under the RUSH name.
- Capital: $1B investment funded by Endeavor.
- Credit: Moody's sees credit positives for both (Rush A1, Endeavor Aa3); the systems haven't decided whether to refinance or restructure outstanding debt.
- Timing: targeted close in early 2027 after regulatory review.
- Opposition: nurses' union leaders urged regulators to block any merger that fails to guarantee services are protected (Chicago Sun-Times).
- Context: Endeavor is itself the rebranded NorthShore – Edward-Elmhurst Health.
HealthPartners and Essentia agree to combineCopy anchor linkCopied
HealthPartners and Essentia Health announced board approval of an affiliation agreement to combine on Sept. 29. Minnesota's attorney general describes it as HealthPartners' proposed acquisition of Essentia and is reviewing it under the state's health care transaction law, Minn. Stat. 145D (AG).
- Scale: 22 hospitals, 135+ clinics, 6,000 clinicians and 45,000 colleagues. Combined revenue tops $12B (HealthPartners >$9.3B and Essentia >$3.2B in FY2025), and HealthPartners runs health and dental plans with 1.6M members (Chief Healthcare Executive).
- Governance: the combined organization takes the HealthPartners name, while Essentia facilities keep the Essentia Health name. One community-based board. HealthPartners CEO Andrea Walsh leads; Essentia CEO David Herman becomes president of combined clinical care group operations.
- Timing: effective Jan. 1, 2027, pending the Minnesota public interest review and federal filings.
- Opposition: the Minnesota Nurses Association raised serious concerns (MPR News).
- Context: Essentia and Marshfield Clinic Health System called off their planned combination in January 2024; Marshfield joined Sanford Health in January 2025. Kaufman Hall counted HealthPartners–Essentia as one of Q3's 2 mega-mergers, alongside Erlanger–Prisma.
Sutter absorbs Allina as its Upper Midwest DivisionCopy anchor linkCopied
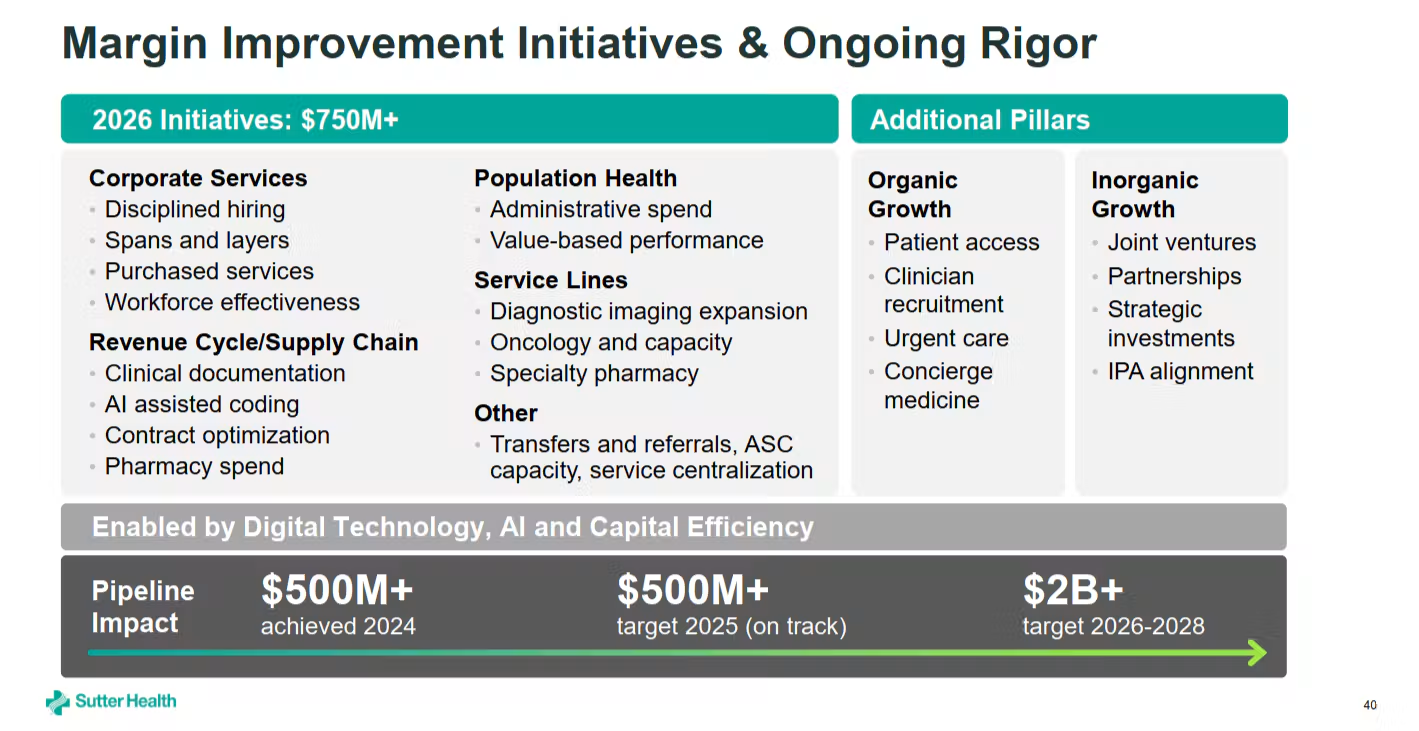
Sutter Health and Allina Health signed a letter of intent on March 17, 2026 and a definitive agreement on May 21, 2026 (deal site). Allina becomes the Upper Midwest Division of Sutter Health (Sutter), a structure a company representative described to Fierce as similar to a member substitution. Minnesota's AG is reviewing it as Sutter's proposed acquisition of Allina under 145D (AG).
- Scale: a ~$26B combination across 39 hospitals and 88,000 people, including 18,000 aligned physicians. Sutter reported $19.8B in 2025 revenue; Allina reported $6B with a $95.4M operating loss (Fierce).
- Governance: Sutter CEO Warner Thomas leads the combined system; Lisa Shannon stays president and CEO of Allina, which keeps its name, brand and Minneapolis regional headquarters.
- Capital: more than $2B of investment committed in Minnesota and western Wisconsin.
- Timing: expected to close by the end of 2026, pending state and federal review; the deal site says it remains on track.
- Opposition: unions are demanding a written community benefits agreement (Minnesota Reformer); the Minnesota Farmers Union came out against it Oct. 1; stakeholders in California have also raised concerns (Healthcare Dive). Ya know, the usual.
- More: the Warner Thomas Playbook
Ascension closes on AmSurgCopy anchor linkCopied
Ascension announced its agreement to acquire AmSurg on June 17, 2025 and closed it on June 4, 2026 (Ascension FY2026 audited financials).
- Price: ~$3.8B per Ascension's audited statements. Bloomberg reported ~$3.9B at announcement, when Ascension declined to disclose a figure (Fierce).
- Footprint: AmSurg had 250+ ASCs across 34 states at announcement; with it, Ascension's total ASC footprint now tops 300 (Becker's ASC).
- FTC: a final consent order approved Aug. 25, 2026 requires Ascension to divest 7 AmSurg ASCs, 6 of them to SCA (FTC).
- Operating model: Ascension keeps AmSurg's physician-led joint venture and governance model.
- Context: Ascension narrowed its fiscal 2026 operating loss by $371M to $120M (Becker's) and has gone from ~139 hospitals to ~90 wholly owned or consolidated hospitals over roughly 3 years
- More: Ascension Seals the Deal
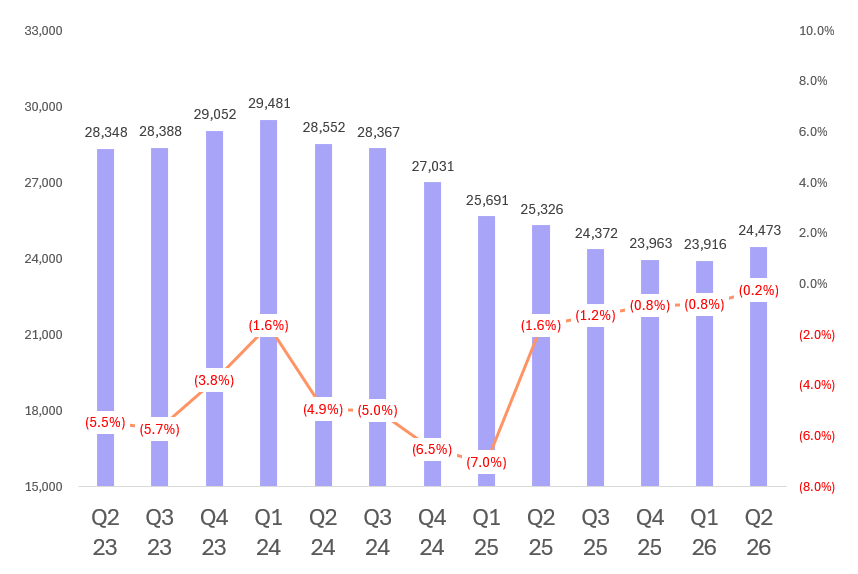
Ascension Total Rolling Revenue and Rolling Operating Margin (by calendar year):
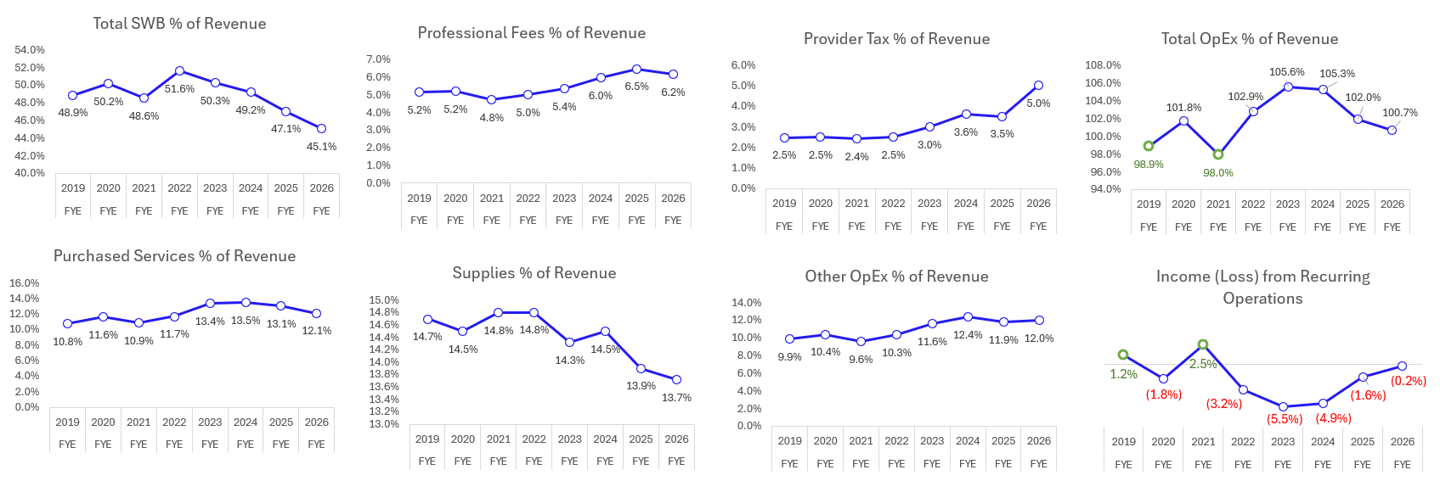
Ascension Common-Sized financials:
Beyond health systemsCopy anchor linkCopied
- Waystar (reported). Reuters reported Sept. 15 that Waystar is exploring options including a sale that could take it private, with Evercore and Barclays advising and the process at an early stage; no bidder has been named and Waystar declined to comment (Reuters via WHBL). EQT (13%) and CPPIB (10%) remain the largest holders of a company Reuters valued at ~$5.2B.
- Option Care Health to CD&R and McKesson, $5.8B. CD&R (~51%) and McKesson (~49%, ~$1.4B) agreed Oct. 6 to take Option Care private at $32.05 a share, a ~37% premium and ~$5.8B enterprise value, with a framework for McKesson to later acquire CD&R's interest (8-K, Ex. 99.1). Close is expected in the first half of 2027.
- Humana's CenterWell clinics and BlackRock, $2.8B. Funds managed by BlackRock's HPS will buy Welsh, Carson, Anderson & Stowe's equity in Humana's CenterWell Senior Primary Care JVs, valued at ~$2.8B, and become majority owner of a new JV covering nearly 150 clinics that CenterWell continues to manage (Humana 8-K exhibit). Unlike the WCAS structure, the new JV has no put option, CenterWell can start buying clinics back in 2028, and close is expected in Q4 2026.
- Since the new joint venture does not include a put option, Humana expects a significant reduction in the liabilities on its balance sheet due to the removal of the put arrangements for the existing joint ventures, with BlackRock receiving certain protections. All in, Humana anticipates a significantly lower cost of capital under the new joint venture, reflecting the maturity of the business.
- Cencora to acquire American Oncology Network, $2.4B EV. Cencora, already a ~4% owner, will pay ~$1.7B to take its stake in AON to 75%, valuing the 350+ provider, 21-state network at a $2.4B enterprise value ($2.3B at close plus up to $100M in CVRs) (Cencora). It follows Cencora's ~$5B OneOncology majority deal ($7.4B EV) announced in December 2025.
- Horizon BCBSNJ to acquire Summit Health New Jersey, including NJ CityMD. Horizon confirmed an agreement to acquire Summit Health's New Jersey business, including the CityMD urgent care sites in the state (ROI-NJ). reported value of more than $1B (BINJE)
- Labcorp to buy more BioReference assets from OPKO, up to $872M. Labcorp will pay $722M in cash at close plus an earnout of up to $150M tied to 4Kscore revenue for BioReference's clinical and women's health, urology and corrections testing businesses and 80+ patient service centers, which it expects to add ~$250M of revenue in year 1 (Labcorp). It's Labcorp's 3rd BioReference carve-out since 2024, after deals for $237.5M and up to $225M.
Miscellaneous MaddeningsCopy anchor linkCopied
As we all should expect from this incredibly volatile Texas team, after coming off 2 unranked losses (including a home loss to Florida), Texas went and beat a top 10 team in the country in Ole Miss on Saturday, squeezing it out by 7 despite a 24-3 lead. I can’t see us running the table with our remaining schedule, but I do think we’re the first team in / out with 3 losses, so my expectation as a super fan, after expecting a national title run, is now firmly set there. A far cry from where I was thinking this team was the Friday before Texas-OU but alas, that’s college football for ya.
Hook ‘em!
Thanks for the read! Let me know what you thought by replying back to this email.
— Blake