Hospitalogy

🏥 Optum wins again

Blake Madden · JUN 27

Good morning, Hospitalogists,


If you’re reading this then that means I’ve successfully escaped the 115 degree heat index Dallas summer and I’m enjoying the cool breeze coming off the waters of Lake Tahoe. Feels good fam.


Optum is also enjoying its own victories. More on that in a sec!

VERTICAL INTEGRATION

Optum wins again, snatches Amedisys away for $3.3BCopy anchor linkCopied

I thought I was going to get a good, clean week off from healthcare M&A but alas, Optum had other plans for me! On Monday, June 26, national home health and hospice player Amedisys announced plans for Optum to acquire the firm at $101 per share, or over $3.3 billion.


If you recall, Amedisys had previously announced its intention to merge with Option Health Care to create a $10 billion enterprise at the time. I broke that merger down here - and the TL;DR is that both analysts and those on the outside looking in felt dubious about the deal prospects.


Smelling a weakness, the Optum empire stepped in, offering Amedisys a much more shareholder friendly all-cash deal in the following weeks. Looks like the deal was preferable for all parties. And if you’re a longtime reader of Hospitalogy, you know that UnitedHealth Group rarely - if ever - loses.


So what does this mean for UnitedHealth Group and healthcare at large?


Between LHC Group and now Amedisys (with the assumption that the deal goes through), Optum likely holds around 10% market share in home health and tacks on another potential growth funnel in high acuity at home programs, Contessa, on its growing list of post acute services.


I also have to wonder what the smaller mom and pop home health agencies (I mean, even the PE-backed ones) think about the growing payor presence in the home health space.


With labor issues, reimbursement cuts (and not getting better any time soon), growing Medicare Advantage penetration, and the encroachment of managed care-owned home health assets, there is plenty of reason to be worried if you’re a home health agency. And if you ARE a home health agency, I’d love to hear how you’re thinking about these threats.


As far as healthcare is concerned, the trend of vertical integration looms large, leading me to wonder…”who gets gobbled up next?”


The ramifications on healthcare services, antitrust, and ultimately patient care should not be discounted. I’d encourage lawmakers to continue to develop vertical antitrust guidelines, especially for healthcare.

ENABLEMENT

Aledade Raises $260M and the Advanced Primary Care Space stays red hotCopy anchor linkCopied

Enablement platform Aledade raised another $260M, announced on June 21. That brings up Aledade's valuation to a reported $3.5B. In June 2022 (a year ago) Aledade raised a $123M Series E at a $3.1B valuation.


At that time it was EBITDA positive with revenue of ~$300M. Now in 2022, Aledade generated revenues of ~$475M (reported in the press release) and assuming platform contribution of 30%, that brings contribution margin level of profitability to ~$140M.


With the most recent funding, Aledade has raised over $660 million to bring risk-based practices to its primary care partners.

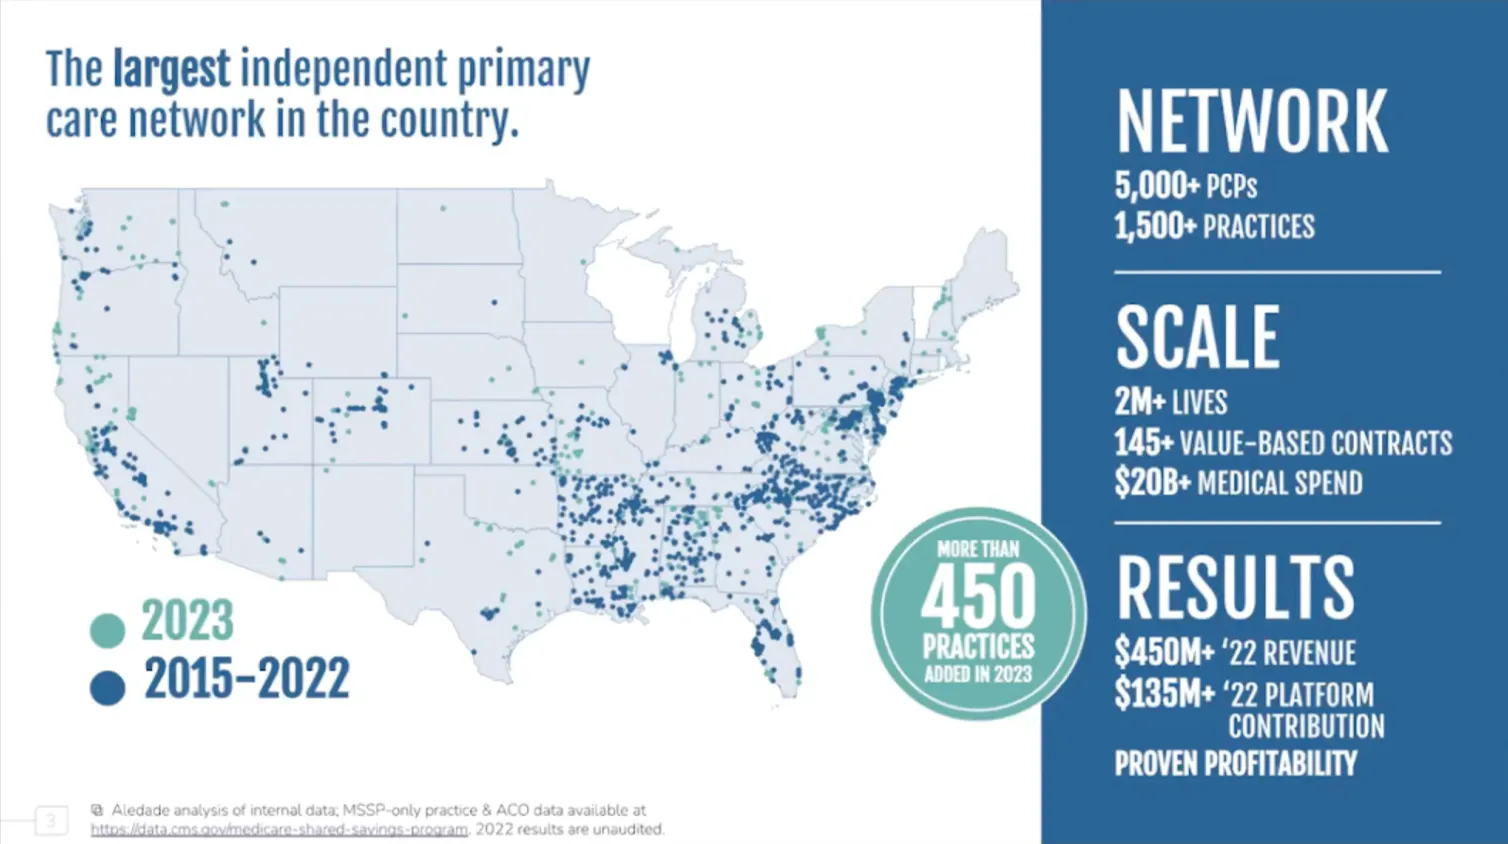
Aledade's footprint is nationwide and includes impressive growth in PCP partners for 2023:

  • 5,000+ PCPs
  • 1,500 practice locations, and
  • 2M+ lives under management

Which is up from ~1,000 independent practice locations and 1.4M lives under management as of June 2021.

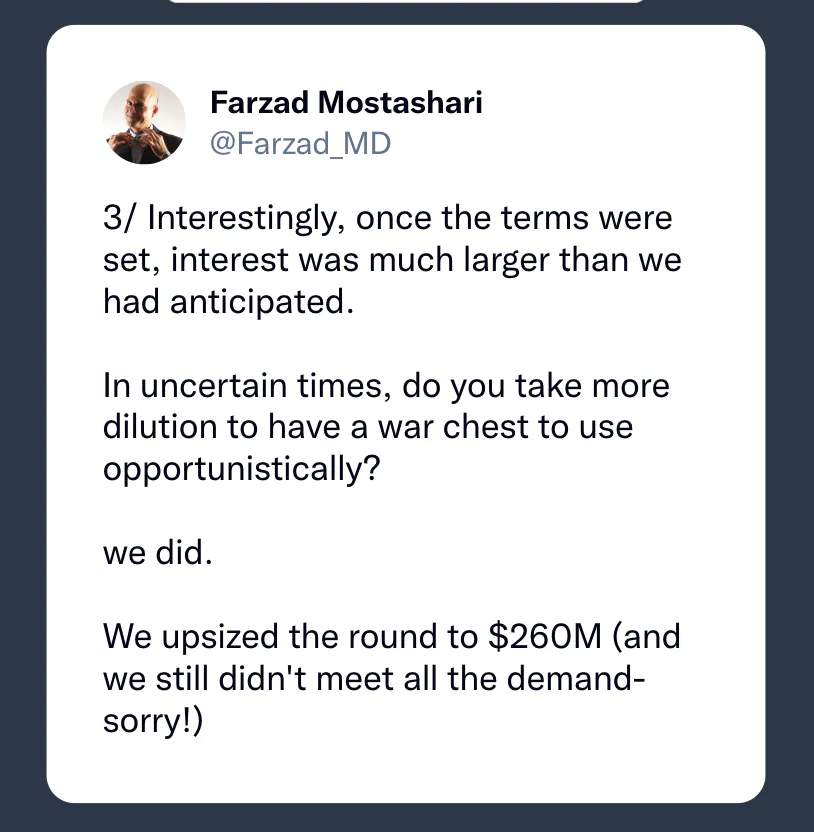
Aledade’s CEO Farzad Mostashari shared some behind the scenes footage on the most recent raise in the current funding environment, including considerations as a public benefit corporation.

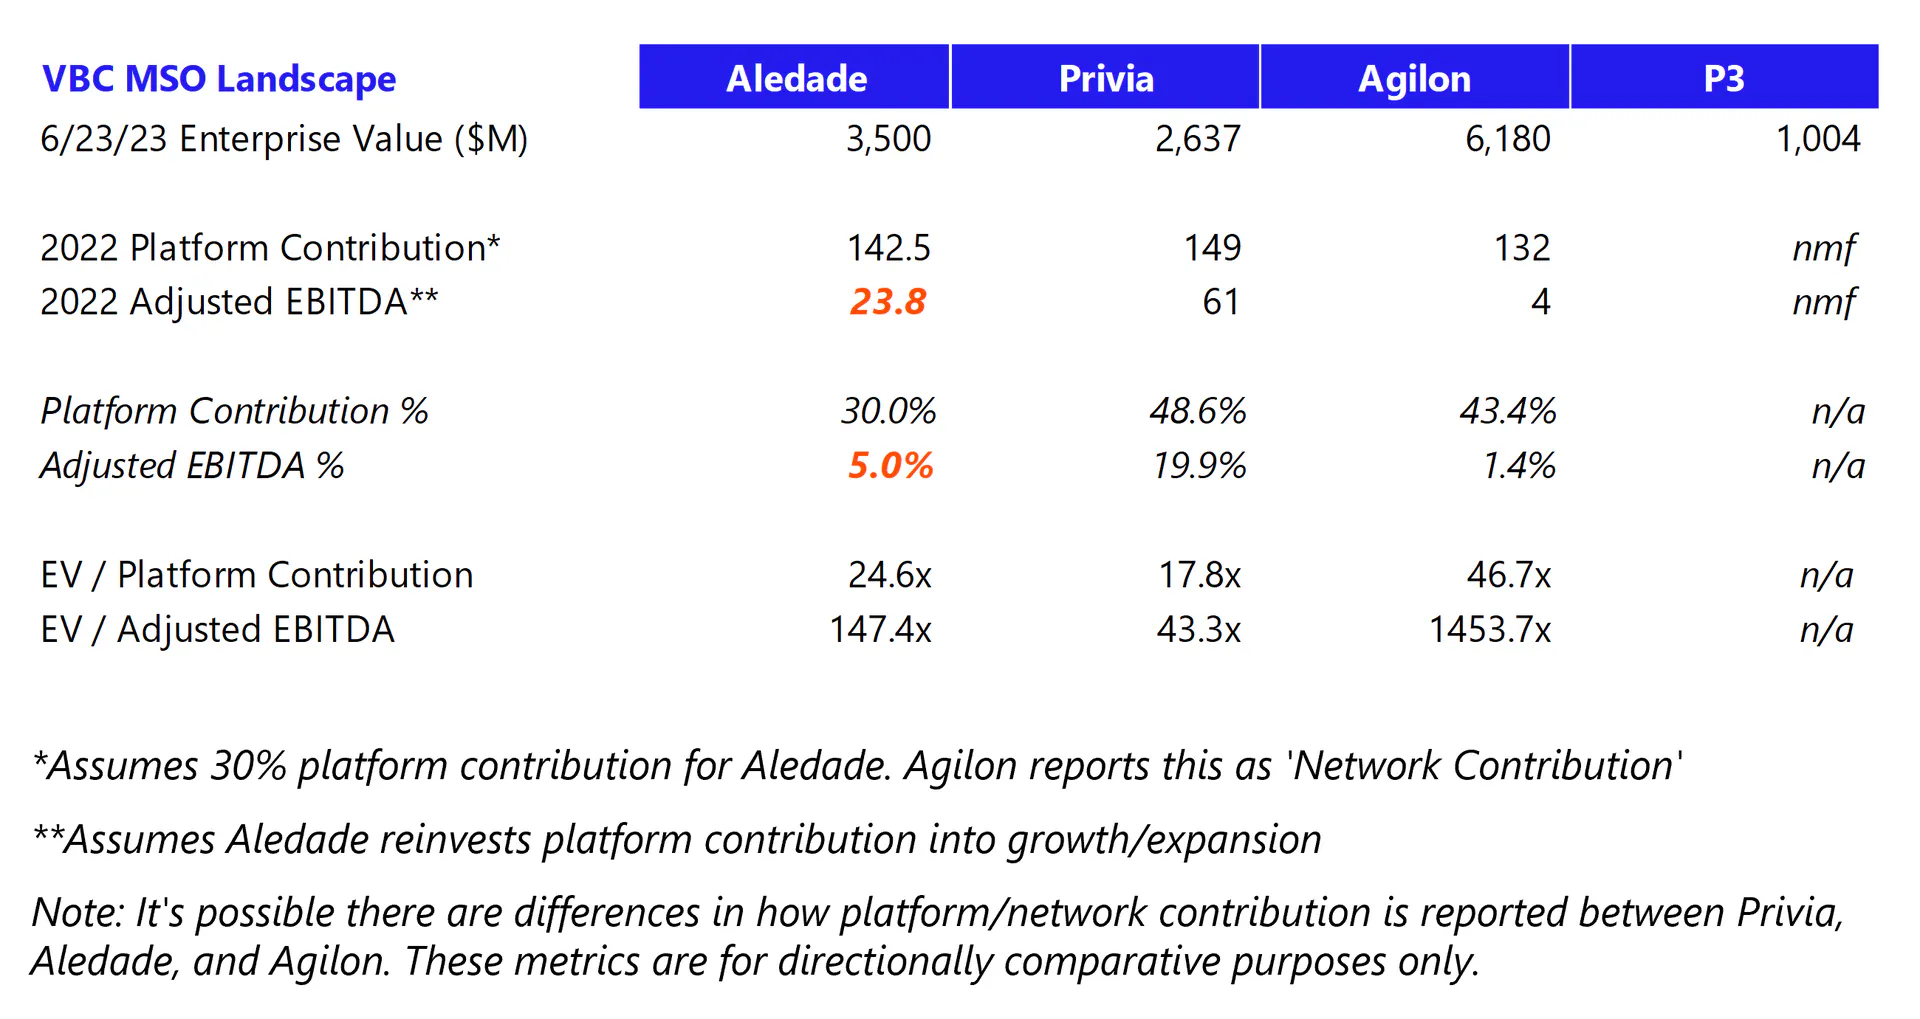
As far as valuation considerations and piecing together somewhat private information from Aledade (along with a VERY rough EBITDA assumption), here’s a rough comparison of the enablement landscape: 

Working with somewhat imperfect information, but based on reported information, Aledade’s reported valuation implies a platform contribution multiple of ~25x and a 2022 revenue multiple of 7.8x.


Given the above information, Aledade's private value now implies a higher valuation than its publicly traded peer Privia Health (~$2.7B enterprise value) but lower than Agilon (~$6.4B enterprise value). I’m not an equity analyst but that Privia fact surprised me.


The fundraising announcement also bucks the macro trends as enablement firms and value-based care players continue to see funding and growth spurred by Medicare Advantage, ACO REACH, and MSSP tailwinds - though Aledade did mention some dilution in that tweet above.


Bigger picture: M&A and venture activity in advanced primary care continues to chug along, and there's a particular focus on enablement/platform level plays as well as technology/analytics/infrastructure.


Take the recent slew of advanced primary care activity, for example:

  • CVS-Oak Street deal ($10.6B)
  • Humana-Welsh Carson - Centerwell developments
  • Amazon-One Medical deal ($3.9B)
  • VillageMD-Summit ($8.9B) and VillageMD-Starling Physicians
  • CVS-led Carbon Health deal $100M fundraise (and led the Monogram Health fundraise)
  • Pearl Health fundraise $75M
  • Vytalize Health fundraise $100M
  • Wellvana fundraise $84M
  • Humana-ChenMed partnership extension

Lots more to come in this red-hot space!


Resources:

  • Aledade 2022 raise - $123M Series E (Link)
  • Aledade 2023 raise - $260M Series F (Link)
  • Farzad Mostashari Twitter thread (Link)
  • Lightspeed Aledade investor memo. (Link)
  • My writeup on enablement platforms (Link)
  • My writeup on Aledade's decision to become a public benefit corporation (Link)

MARKET MOVERS

Partnerships and Strategy Updates:

Anything affecting decision making in healthcare - notable moves and strategies for healthcare operators to keep on your radar.


Friday Health in Receivership: After the states of Colorado and North Carolina put Friday Health Plans into receivership, Friday no longer has control of any of its health plans in its entire 7 state footprint. (Link)


Employer-sponsored growth: Commercial insurance enrollment is expected to remain stable through 2025 at around 155 million covered individuals, per a recent Health Affairs study. (Link)


MSO-PC structures: VMG Health wrote a nice overview of common structures of private equity friendly PC models, diving into the most common specialties, types of management fee structures, valuation considerations, and length of service agreement. (Link)


Walmart expansions: The retail giant is opening up 3 Walmart Health sites in Florida. (Link)


HCA under fire: HCA has been accused of transferring hospice patients at a higher rate than the national average, therefore reducing its reported hospital mortality rates. HCA has also in the past been accused of admitting a higher percentage of ER patients as inpatient hospital admissions. Lots of smoke, no fire. (Link)


Partnership Announcements:

  • Oschner Health announced a partnership with the University of Texas MD Anderson Cancer Center to develop advanced cancer care treatment plans through an integrated care delivery model. (Link)

Finance and M&A Updates:

Anything related to the financial side of healthcare and M&A.


Healthcare Services M&A declines slightly: PwC’s recent healthcare dealmaking report showed that deal volumes hit $85.2B in value stemming from 1,661 transactions. It’s a 4% decrease in deal activity year-over-year. (Link)


CARD ABA is shutting down. (Link)


Digital Health and Innovation Updates:

Notable fundraising announcements, health tech product launches, breakthrough innovation, and reasons for optimism.


Elation Health announced a partnership with Zocdoc to integrate online scheduling and other patient friendly tools into Elation’s EHR. (Link)


Carrum Health partnered with apree health to integrate its Center of Excellence network into apree’s navigation platform. (Link)


Fundraising Announcements:

  • AvoMD, a clinical decision support and workflow firm, raised $5M. AvoMD’s very own Yair Saperstein was excited to share the news with me. When I asked him what’s next in their journey, he responded with plans for deeper AI integration, auto-recognition of patient phenotypes for recommendations, and expansion of the AvoMD team. (Link)
  • Karoo Health, a cardiology enablement firm, raised $3.4M in seed funding. (Link)
  • Caraway, after emerging from stealth with $10.5M in 2022 and launching a college women’s health service raised another $16.75M in funding. (Link)
  • DUOS, a tech platform that helps manage senior benefits, raised $10M. (Link)
  • DexCare, a data intelligence and logistics startup, raised $75M. (Link)


The Healthcare Hype Cycle: AI

This is the spot where I cover the buzzy, hot topics in healthcare. Currently the flavor of the month is AI in Healthcare.


AWS launched a new artificial intelligence program along with $100M in funding to connect machine learning and AI experts with AWS customers. Healthcare and life sciences firms will be a top priority in the initiative! (Link)


OSF Healthcare developed a new AI to assist cancer care navigation. (Link)


Medical Futurist dove into 10,000 healthcare AI patents. (Link)


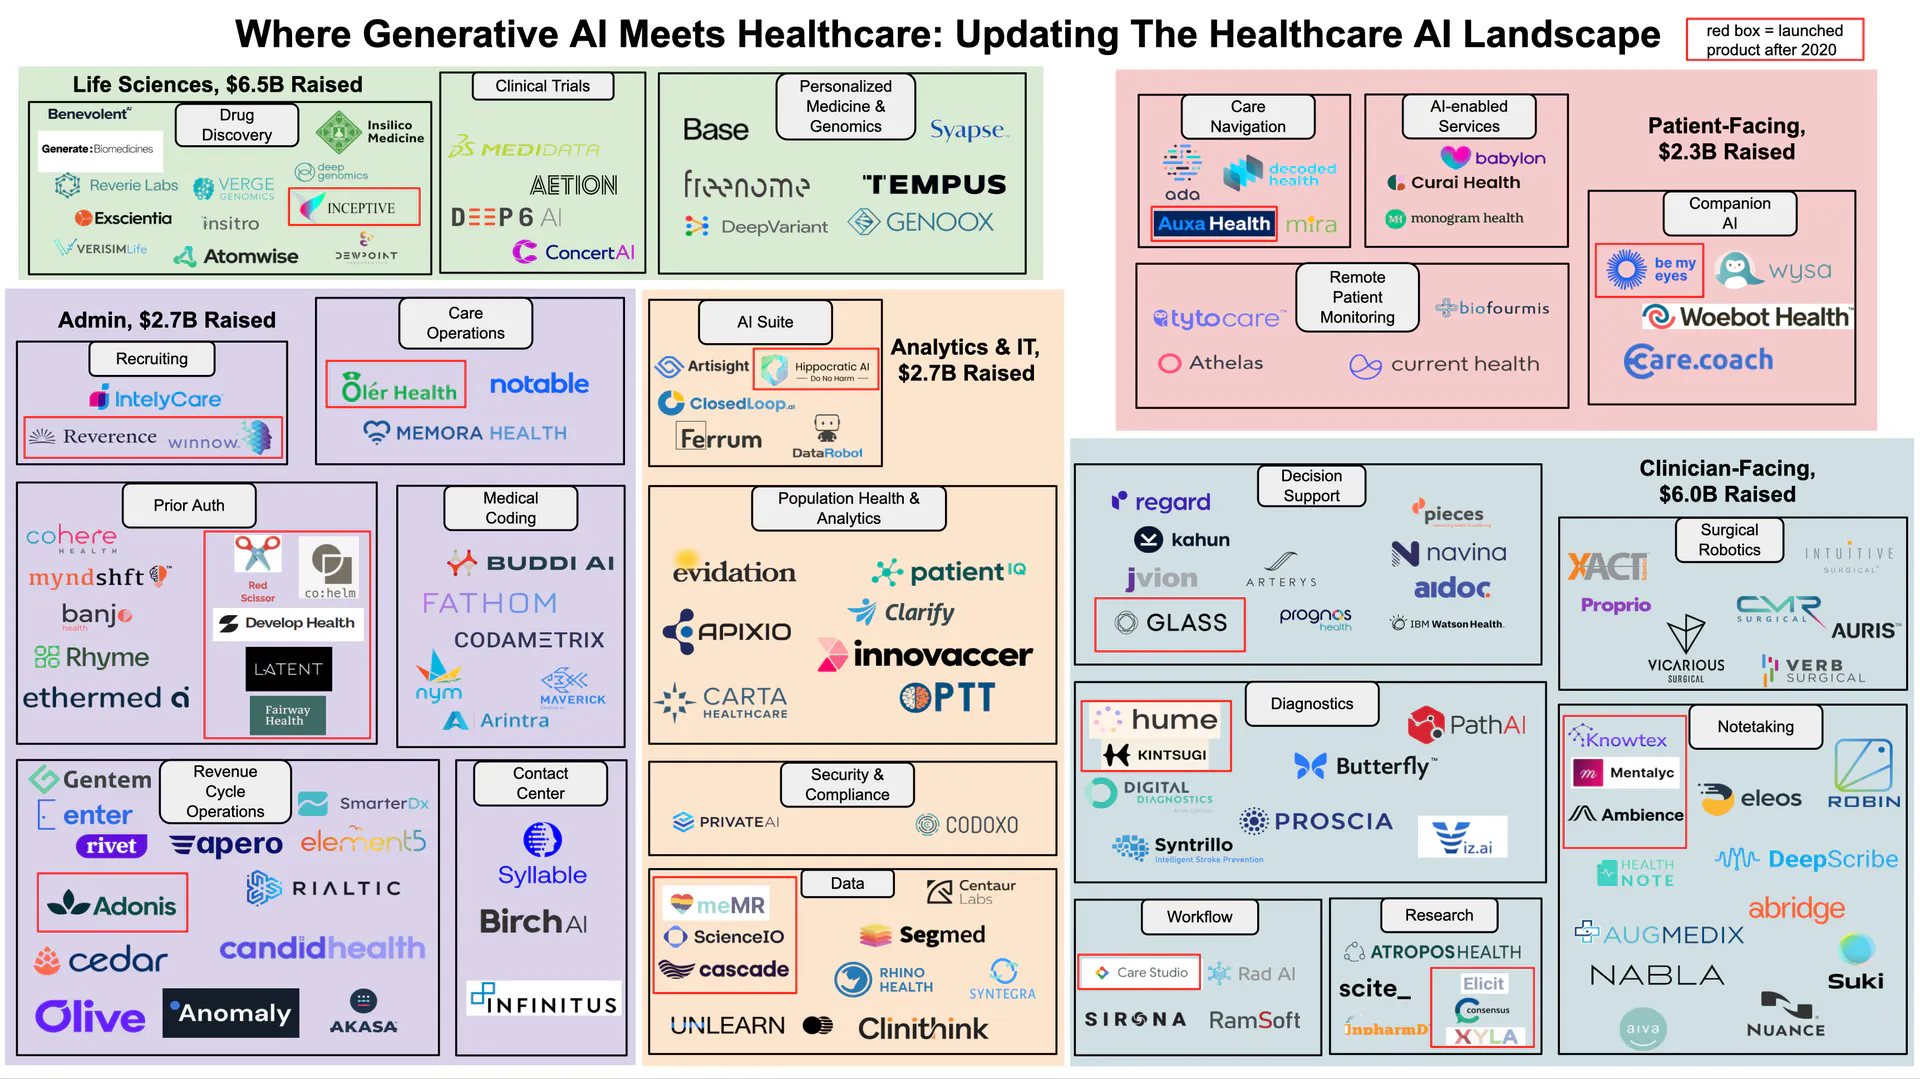
Healthcare AI Landscape: Justin Norden, Jon Wang, and Ambar Bhattacharyya put together an excellent, well-researched piece on the healthcare generative AI landscape, diving into specific areas of investment and the players involved across various segments of healthcare. From someone who know how long something like this piece of content probably took, please give the essay a read and drop a subscription! (Link)
HOSPITALOGY TOP READS

  • This story related to the Harvard Medical School morgue and a bad actor selling body parts was insane. (Link)
  • Paul Keckley shared some great thoughts on the disconnect between the Fed and healthcare policymakers - “The Fed pays inadequate attention to the healthcare economy.” (Link)

MISCELLANEOUS MADDENINGS

  • So on the second day of Tahoe, we decided to go on a quick hike to a point called Cave Rock. Everything was great and we snapped some beautiful pictures, but a bit of a scuffle unfolded at the bottom of the hike. There was a dog barking at everyone who passed, and the dog’s owner was standing there while waiting for his wife and kids to get down from the top of the hike. And I have to admit - it was a little annoying. But another older gentleman walking with his beloved wife was clearly more than a little annoyed by the barking, that after a few short moments he yelled “can you control your f***ing dog?” I was so taken aback by this remark (and happened to be standing right there) that I laughed, clearly thinking that this guy was joking. But oh no, let me tell you, that man was red in the face and piping mad from this 20 pound chihuahua yelping as if its life depended on it. After a couple more exchanges between this man and the owner, the man threatened to “kick that dog off the cliff” and I decided at this point that it was time for us to get the heck out of there before things escalated further. Anyway the man ended up walking back with his wife but fella..get a grip and get some perspective. How can you be mad while gazing upon something as beautiful as Lake Tahoe?
  • I’m playing the Incline Village Championship course on Wednesday. If you have any intel on the local flora, let me know fam.

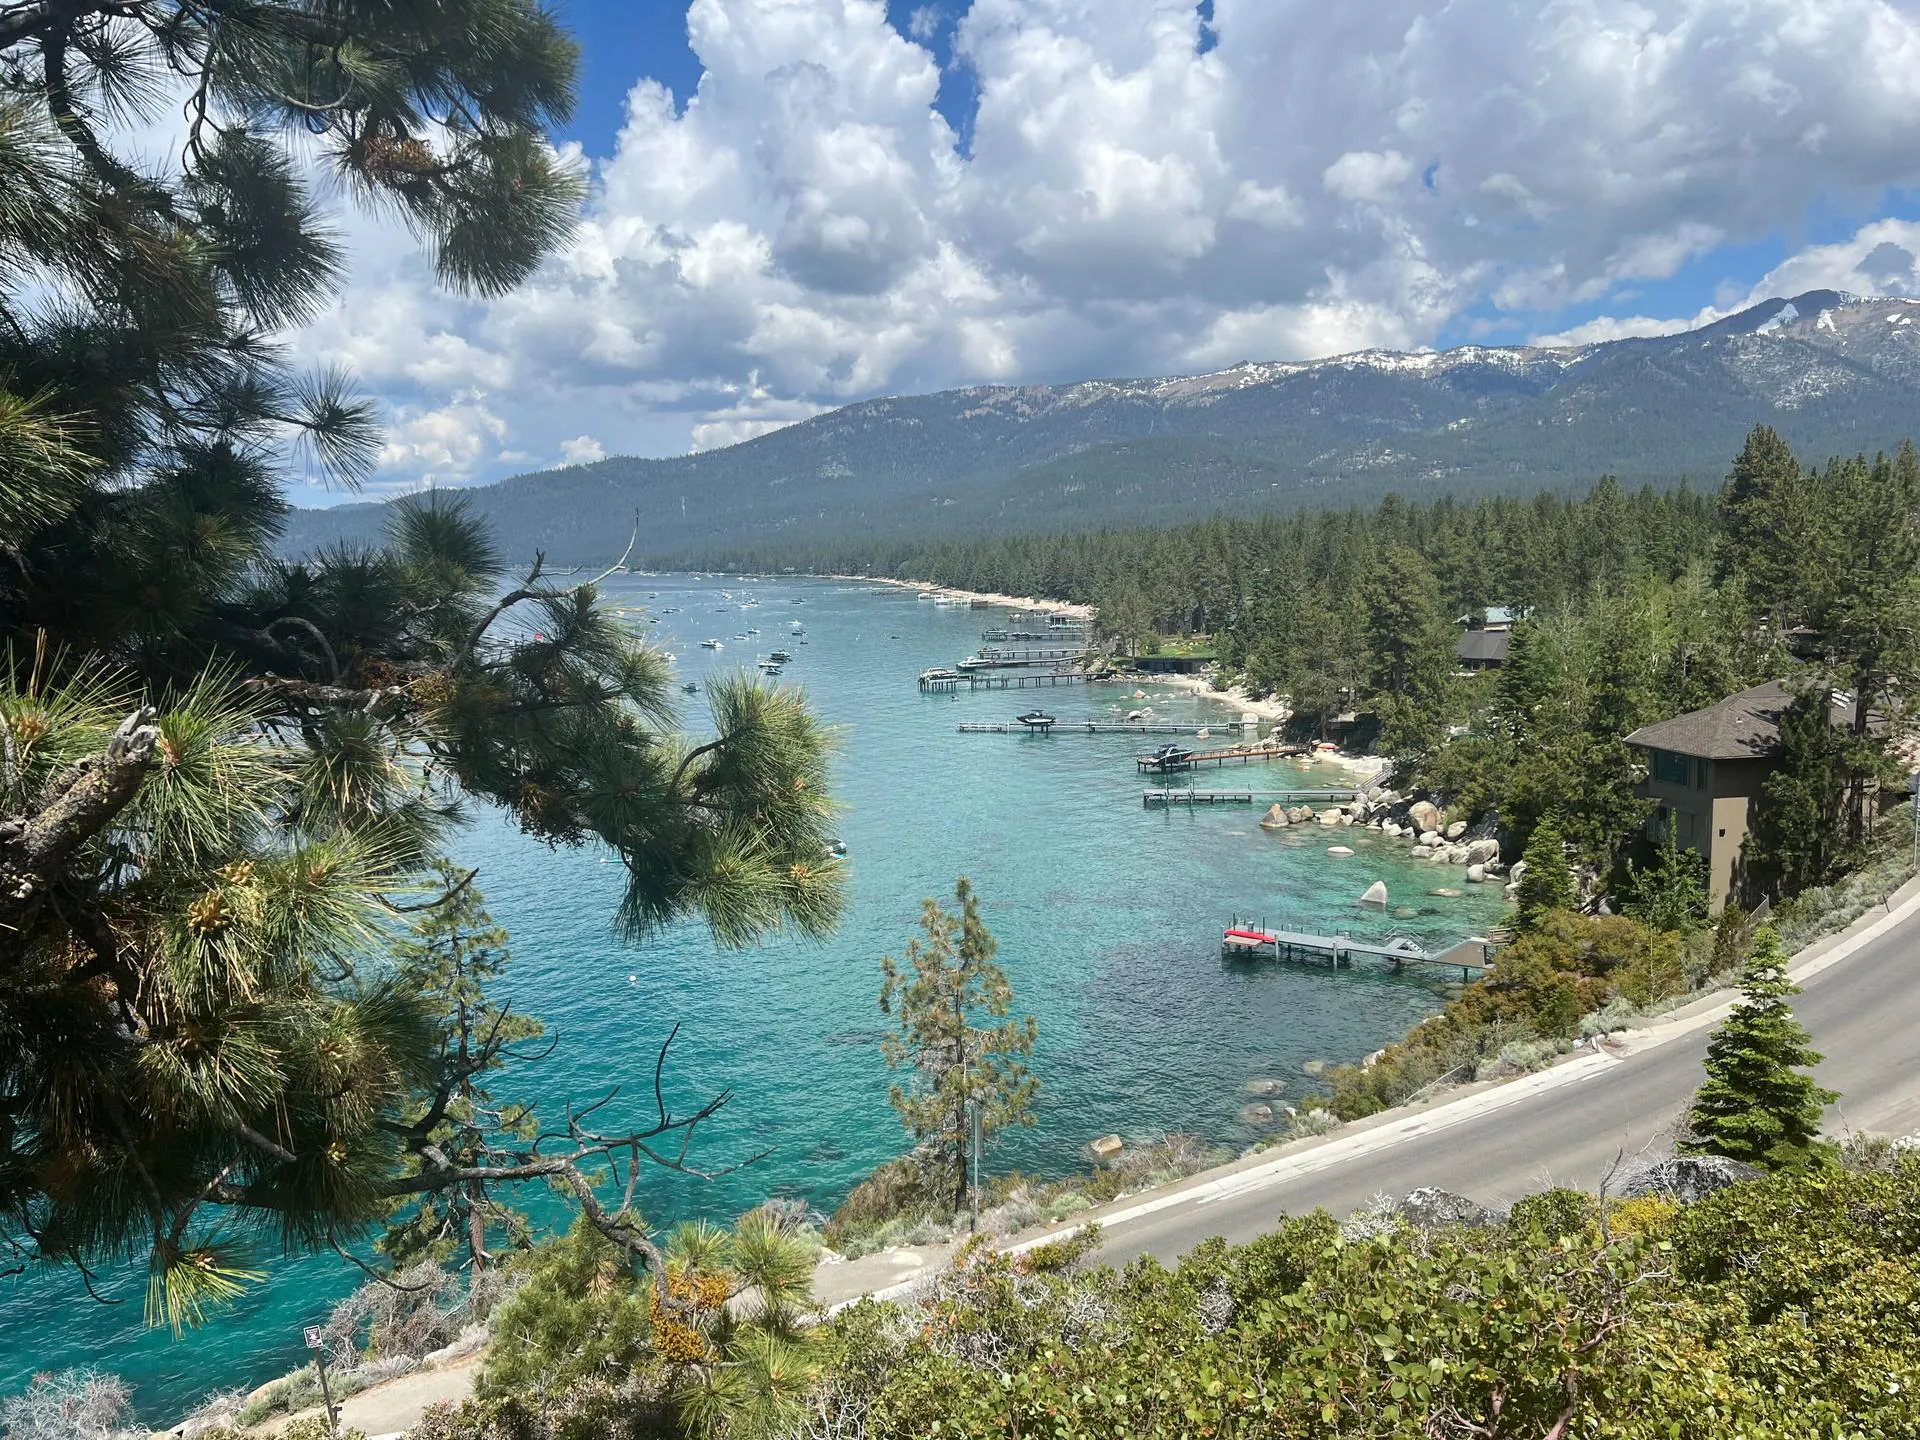
And here's a pic I took today:

Thanks for the read! Let me know what you thought by replying back to this email.


— Blake  

Get Hospitalogy in your inbox

The weekly read for the people running the business side of care delivery.

Written by Blake Madden

By Blake Madden

Hospitalogy

The weekly read for the people running the business side of care delivery.